DS cuts LIG price target 52%; Hanwha Securities keeps 670,000 won
DS cut its LIG target, while Hanwha Securities kept its target and identified new orders and a court decision on whether to suspend bidding restrictions as near-term share-price factors. Both retained Buy ratings.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-09 (KST)
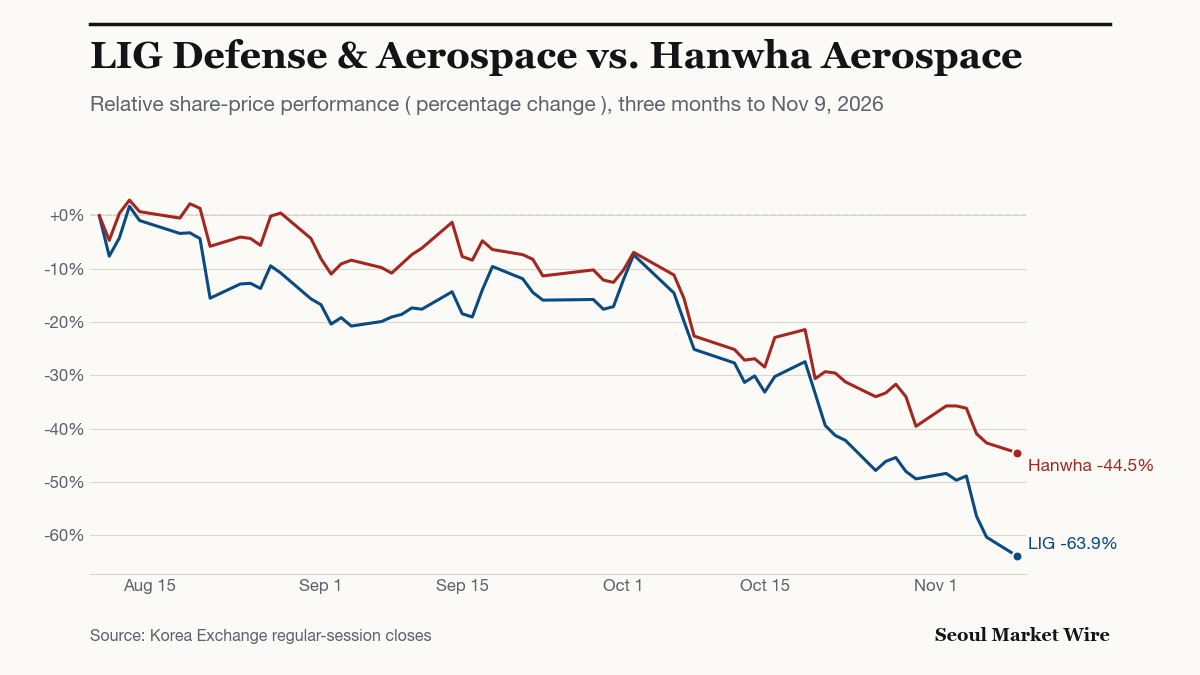
DS Investment & Securities cut its price target for LIG Defense & Aerospace by 52% on Nov. 9, from 1.25 million won to 600,000 won. Hanwha Investment & Securities kept its target at 670,000 won in a report published the same day. Both retained Buy ratings.
The split followed LIG’s third-quarter operating profit of 67.6 billion won, below the consensus cited in both reports. DS also cut its target for Hanwha Aerospace by 24.2%, from 1.65 million won to 1.25 million won, while retaining Buy.
Why did DS cut its target while Hanwha kept its own?
The lower DS target reflected reduced export-margin assumptions following the won’s appreciation and a cut to revenue estimates for the UAE’s Cheongung-II air-defence programme. Its analysts also cited uncertainty over the timing of revenue recognition on export projects.
For Hanwha Securities, the earnings miss left the longer-term growth outlook intact. The brokerage identified new orders and a court decision on whether to suspend LIG’s domestic public-procurement bidding restrictions as key near-term share-price factors. The restrictions concern eligibility to bid for domestic public contracts.
Against LIG’s Nov. 6 closing price of 326,000 won, the targets implied upside of 84.0% for DS and 105.5% for Hanwha Securities. These comparisons use the session before the reports were published, rather than the latest share price.
DS cited LIG’s forecast of an order backlog of about 28 trillion won at the end of 2026.
Who is exposed to a stronger won?
Currency effects differed across the five defence companies covered in the DS sector review. DS said LIG had reported a roughly 5-percentage-point decline in its third-quarter export margin. The sector review did not specify the comparison period for that margin change.
Separately, the review compared an average exchange rate of 1,418 won per dollar in Q3 with 1,364 won per dollar on Nov. 6, a decline of about 3.8%. The Nov. 6 observation came after quarter-end; the comparison does not establish how much of LIG’s third-quarter margin decline resulted from currency movements.
Further won appreciation could pressure margins on LIG’s exports in the fourth quarter, according to DS. Korea Aerospace Industries’ aircraft exports had a different exposure: their high dollar-denominated costs meant a stronger won could benefit margins. The brokerage distinguished those aircraft exports from KAI’s aircraft-parts business, where further won appreciation would be a burden.
When does the delivery mix improve?
Lower third-quarter deliveries increased Hanwha Aerospace’s fixed-cost burden, while a stronger won also weighed on earnings. The DS roadshow review expected deliveries to Poland to accelerate again in the fourth quarter of 2026.
For 2027, its analysts projected higher Polish K9 deliveries and recognition of the remaining volumes under Poland’s first Chunmoo execution contract. DS expected K9 and K10 deliveries to Romania in the first half of 2027.
DS’s revised target of 1.25 million won implied 89.4% upside from Hanwha Aerospace’s Nov. 6 closing price of 660,000 won.
Sources
- DS Investment & Securities — LIG Defense & Aerospace: The big picture holds, near-term uncertainty widens (Nov. 9, 2026) stock.naver.com
- Hanwha Investment & Securities — LIG Defense & Aerospace 3Q26 Review: Below expectations; long-term view intact, orders and sanctions key to a near-term rebound (Nov. 9, 2026) stock.naver.com
- DS Investment & Securities — Hanwha Aerospace [NDR review]: The worst mix passes, the best mix arrives (Nov. 9, 2026) stock.naver.com
- DS Investment & Securities — Defence: Wrapping up Q3 results, points to note (Nov. 9, 2026) stock.naver.com