KAI's Q3 profit beats forecasts as brokers flag delivery risks
Shinhan estimated that operating profit missed consensus by 8.7% after removing the currency benefit and adding back one-off charges. Daishin and iM cut their targets.
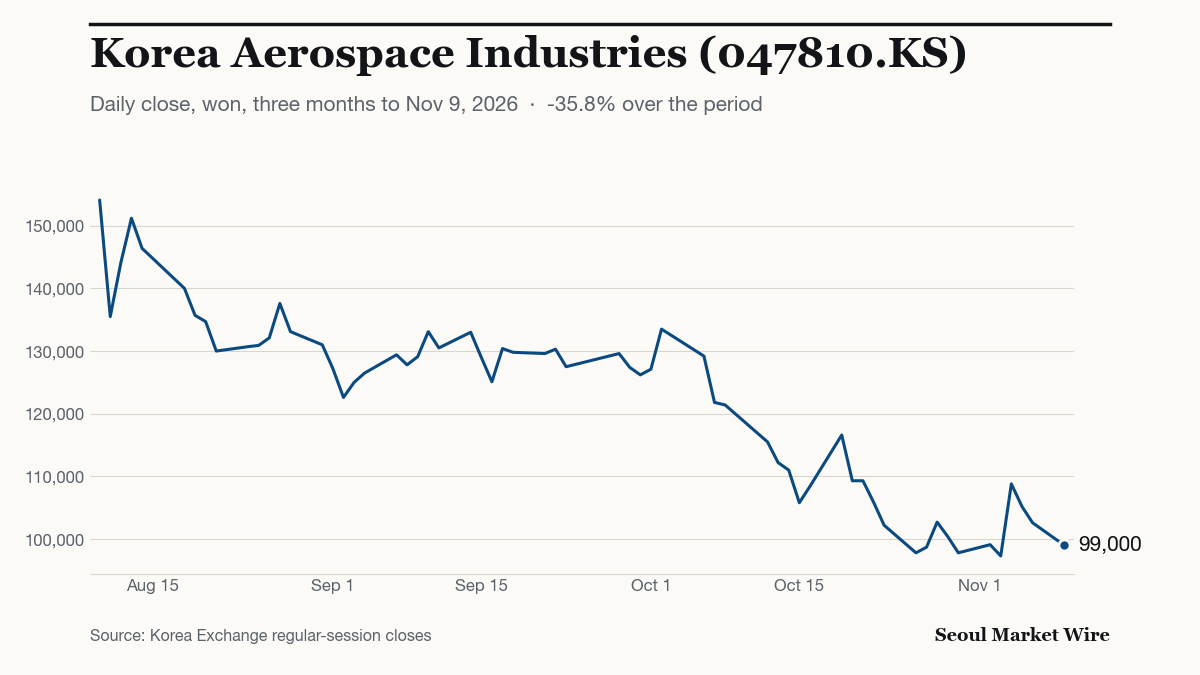
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-09 (KST)
Target cuts followed Korea Aerospace Industries (KAI)’s third-quarter profit beat as brokers flagged helicopter delays and questioned how much of the earnings improvement would persist. In Nov. 4, 2026, reports, Daishin Securities cut its target 7.0% to 173,000 won, while iM Securities lowered its target 10.6% to 135,000 won.
Exchange-rate-related revisions to estimated project costs helped lift operating profit above forecasts. After removing the currency benefit and adding back one-off charges, however, Shinhan Securities estimated profit below consensus in its Nov. 4 analysis.
How much of the profit beat was recurring?
Revenue rose 51.6% from a year earlier to 1.0643 trillion won, while operating profit increased 31.9% to 79.4 billion won, a 7.5% margin. Profit exceeded the 75.3 billion won market consensus cited by DS Investment & Securities in its Nov. 4 review and the 76 billion won consensus cited by SK Securities on the same date. SK described the result as in line with expectations.
The currency benefit was about 40 billion won, against roughly 30 billion won of one-off charges, according to the Nov. 4 analysis by Kiwoom Securities and SK’s review.
Estimates differed in scope. One-off costs including consolidation adjustments totalled about 37 billion won, according to Hanwha Investment & Securities’ Nov. 4 review. The currency benefit was about 30 billion won in Yuanta Securities Korea’s analysis published that day.
For Shinhan, removing the currency benefit and adding back one-off charges yielded operating profit of 69.4 billion won, 8.7% below consensus. This was the brokerage’s adjusted estimate, rather than a separately reported company measure.
What drove the target cuts?
The sample comprises 10 Nov. 4 brokerage reports available on Naver Finance. Their targets have a simple mean of 162,000 won and a median of 161,500 won. These are sample statistics, not a market-wide consensus.
| Brokerage | Target, Nov. 4, 2026 | Report-stated revision |
|---|---|---|
| DS Investment & Securities | 186,000 won | Not shown |
| Kiwoom Securities | 185,000 won | Not shown |
| Yuanta Securities Korea | 182,000 won | Not shown |
| Daishin Securities | 173,000 won | Cut 7.0% |
| Mirae Asset Securities | 173,000 won | Not shown |
| Hanwha Investment & Securities | 150,000 won | Not shown |
| SK Securities | 150,000 won | Not shown |
| Eugene Investment & Securities | 146,000 won | Maintained |
| Shinhan Securities | 140,000 won | Not shown |
| iM Securities | 135,000 won | Cut 10.6% |
The revision column records only changes explicitly described in the Nov. 4 reports. It does not calculate changes against older reports; “Not shown” means no revision is stated here.
Lower earnings estimates and a reduced valuation multiple drove Daishin’s cut. For its target calculation, the brokerage applied a P/E of 30.8 times forecast 2028 earnings attributable to shareholders. Separately, it put KAI’s trading P/E at 20.3 times 36-month forward earnings, against 18.0 times for global peers. Its analysts argued that a first KF-21 export order in the fourth quarter could ease valuation concerns.
Lower valuations at benchmark companies prompted iM’s target reduction. The 146,000 won target was maintained in the Nov. 4 report from Eugene Investment & Securities.
How do delivery delays affect revenue?
An engine defect had disrupted deliveries of KAI’s Light Armed Helicopter, or LAH, according to iM. The brokerage reported a November restart but expected only two or three additional deliveries by year-end, after seven in the first half, leaving roughly 20 aircraft behind schedule.
Its report discussed a potential revenue shortfall of 400 billion to 500 billion won against the original 5.7 trillion won annual guidance. Its financial forecast tables, however, projected 2026 revenue of 5.0763 trillion won, a shortfall of 623.7 billion won. The narrative and tables therefore imply different shortfalls; the report does not explain the difference.
Additional Iraq bad-debt provisions and up to 100 billion won of fourth-quarter in-house development spending were profit risks identified by Yuanta.
On deliveries already completed, the brokerage reported that KAI delivered two KF-21 fighters to the Korean military in the third quarter. Export revenue from Malaysian and Polish contracts was recognised as work progressed.
KAI closed at 99,000 won on Nov. 9, down 3.51% on the day.
Sources
- Kiwoom Securities — Korea Aerospace Industries: Fourth-quarter orders are the key stock.naver.com
- Daishin Securities — Korea Aerospace Industries 3Q26 review stock.naver.com
- Hanwha Investment & Securities — Korea Aerospace Industries 3Q26 review stock.naver.com
- DS Investment & Securities — Korea Aerospace Industries: Order guidance maintained stock.naver.com
- Yuanta Securities Korea — Korea Aerospace Industries 3Q26 review: Earnings and orders both surprise stock.naver.com
7 more sources
- Shinhan Securities — Korea Aerospace Industries: Time to prove it with deliveries and orders stock.naver.com
- Mirae Asset Securities — Korea Aerospace Industries 3Q26 review stock.naver.com
- Eugene Investment & Securities — Korea Aerospace Industries: Everything has bottomed out stock.naver.com
- iM Securities — Korea Aerospace Industries 3Q26: The start of a defence-order revival? stock.naver.com
- SK Securities — Korea Aerospace Industries: Growth in 2027–2028 stock.naver.com
- iM Securities — Full report and target-price history, Nov. 4, 2026 imfnsec.tistory.com
- Maeil Business TV — Korea Aerospace Industries regular-session daily prices mbnmoney.co.kr