Selected SK hynix broker targets span 2.3 million–3.7 million won after record profit
Two brokerage reports assign Buy ratings but differ on earnings forecasts and the valuation of 2027 book value after SK hynix's record third-quarter profit.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-06 (KST)
Two verified brokerage reports put SK hynix’s target price at 2.3 million and 3.7 million won after record third-quarter operating profit. Both carry Buy ratings, but their fourth-quarter earnings forecasts and target valuation multiples differ.
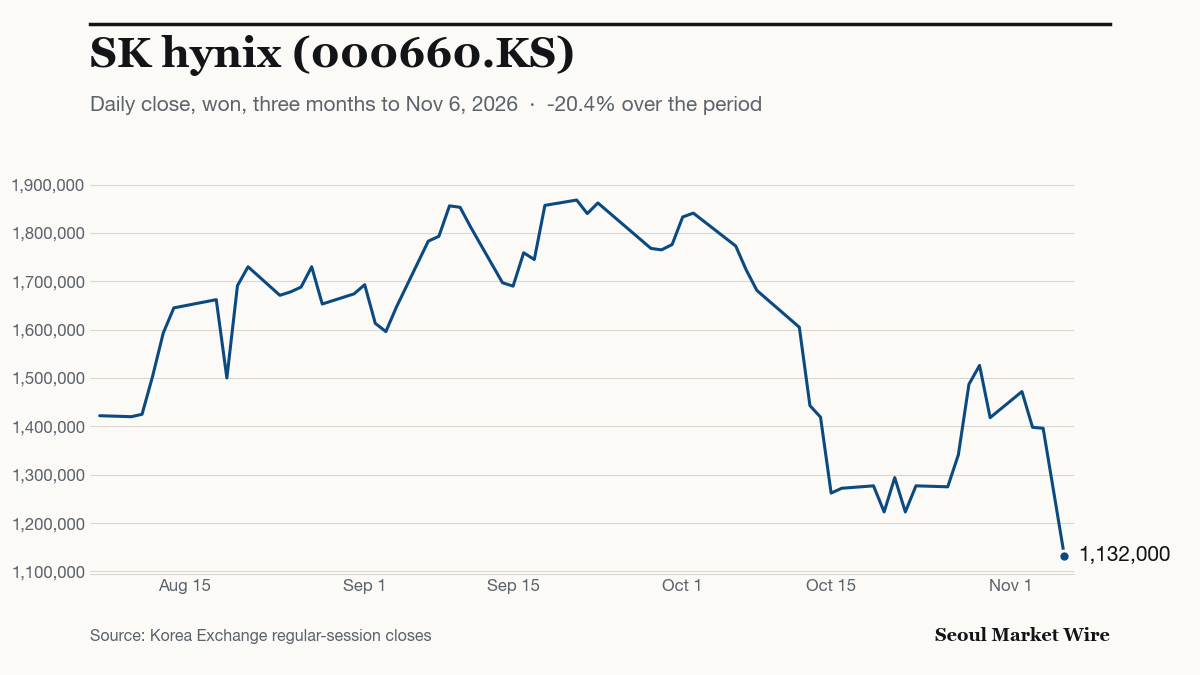
The shares closed at 1,132,000 won on Nov. 6, down 10.44%.
Which targets are being compared?
This comparison is limited to two reports whose targets, ratings and dates were matched against the brokerages’ own publications. It is not a market-wide target range or consensus. Share prices are as of Nov. 6; the report comparison was compiled on Nov. 8.
| Brokerage and original report | Report date (2026) | Rating | Target price |
|---|---|---|---|
| iM Securities | Nov. 4 | Buy | 2,300,000 won |
| Yuanta Securities Korea | Oct. 28 | BUY | 3,700,000 won |
The dates are those of the original reports. Yuanta’s Naver listing is dated Oct. 29.
How much further can earnings rise?
Company results released on Oct. 28 put revenue at 104.6 trillion won and operating profit at 83.3 trillion won, with a margin near 80%. SK hynix attributed growth to stronger memory demand and expanded sales of HBM4 and server products.
Against that result, Yuanta cited an upper-end consensus operating-profit estimate of 80.0 trillion won. For the fourth quarter of 2026, iM forecasts operating profit of 102.3 trillion won, while Yuanta forecasts 118.2 trillion won.
What valuation do those profits warrant?
The 3.7 million won target uses 3.5 times Yuanta’s estimated 2027 book value per share. The 2.3 million won target uses 2.3 times iM’s own 2027 estimate. Both are target-setting multiples for the same forecast year, but the underlying book-value estimates also differ; the multiple alone does not explain the gap.
A lower target does not mean iM expects earnings to fall. Its analysts interpreted the selloff as reflecting market fears of a sharp profit decline in 2028. Their own forecasts show operating profit rising from about 452.8 trillion won in 2027 to 542.0 trillion won in 2028, even as return on equity falls from roughly 66% to 47%.
Why did net profit miss expectations?
Yuanta put profit attributable to owners of the parent at 41.6 trillion won, against its cited consensus of 65.4 trillion won. It attributed the shortfall to foreign-exchange losses of 11.6 trillion won and investment-valuation losses of 22.9 trillion won, including on Kioxia.
The company’s preliminary consolidated net income was 39.7756 trillion won. That is a different measure from profit attributable to owners of the parent; the figures are not interchangeable.
What has the company committed to return?
The company outlined approximately 100 trillion won in 2026 shareholder returns, comprising at least 30 trillion won in cash dividends and at least 60 trillion won in share repurchases and cancellations.
Of a newly approved 20 trillion won repurchase, 10 trillion won is earmarked for cancellation. The remaining approximately 10 trillion won is for employee compensation and excluded from shareholder returns.
The third-quarter dividend totaled approximately 14 trillion won, or 20,000 won per share: 10,000 won reflecting improved earnings and a 10,000-won special dividend linked to Kioxia investment gains.
Sources
- iM Securities — Nov. 4, 2026 report stock.naver.com
- Yuanta Securities Korea — Oct. 28 report, listed on Naver Oct. 29, 2026 stock.naver.com
- SK hynix — Official third-quarter 2026 results and dividend announcement news.skhynix.com
- Yuanta Securities Korea — Official report dated Oct. 28, 2026 05.myasset.com
- iM Securities — Official report posting imfnsec.tistory.com
1 more sources
- Yahoo Finance — SK hynix historical prices finance.yahoo.com