Shinhan sees selective 2027 rally for Korean builders on nuclear, AI work
Shinhan expects project progress and expected earnings contributions to distinguish Korean builders in 2027. Hana's Donghae analysis highlights the importance of tenant confirmation.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-11 (KST)
Korean construction stocks face a more selective rally in 2027, with project progress and expected earnings contributions separating builders, according to Shinhan Investment Corp. Its Nov. 10 outlook puts the sector’s upper-end valuation at 1.1 times book value, below the 2026 peak of 1.3 times, while forecasting a higher share-price floor.
Could US policy proposals redirect data-centre investment?
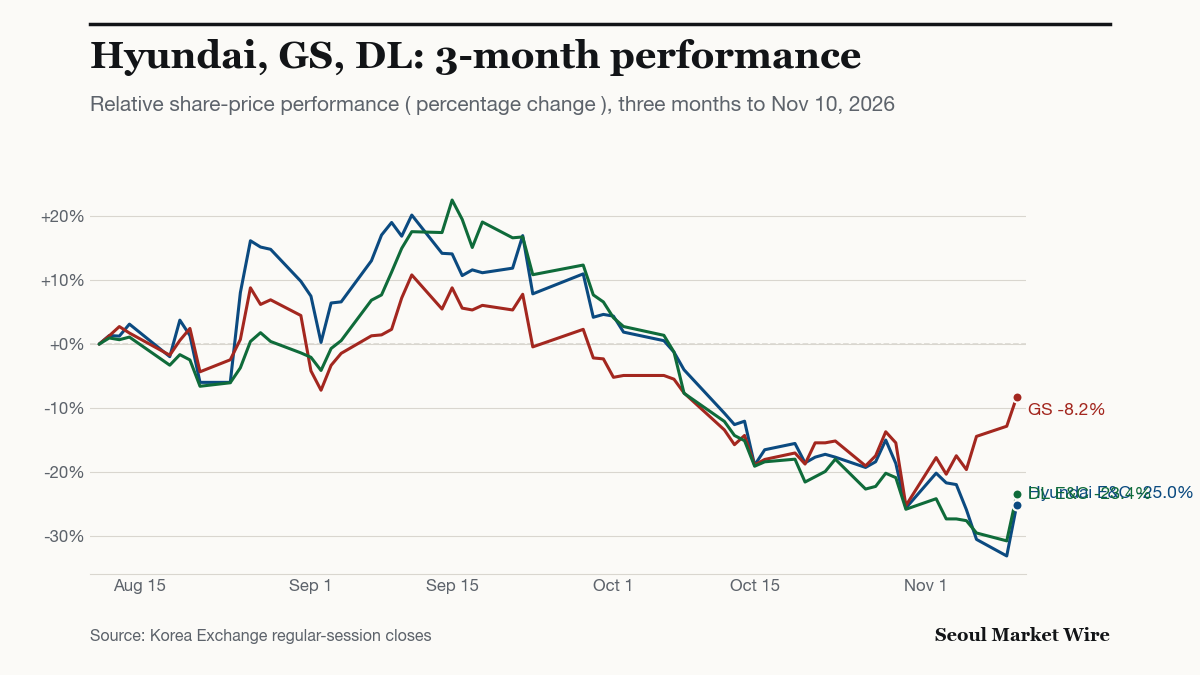
Tighter US development rules, if adopted, could increase demand for leased data-centre capacity in Korea, according to Eugene Investment & Securities’ Nov. 9 analysis. It cited support for moratoriums from the governors-elect in Texas and Ohio. Those positions are policy proposals; the analysis does not establish that new restrictions have taken effect. The brokerage identified GS Engineering & Construction, DL E&C and Hyundai E&C as potential beneficiaries.
Demand could move overseas if US supply cannot keep pace, Hana Securities argued in its Nov. 10 weekly. Its analysts pointed to industrial land outside the Seoul area, available electricity and capital as advantages for Korean projects. Shinhan’s Nov. 9 construction weekly also cited additional data-centre projects as support for builders’ earnings prospects.
Which project milestones matter?
At Donghae, Hana expects a groundbreaking ceremony for a 100MW data centre in late November or early December 2026. The brokerage had not confirmed a tenant when it wrote the report. Its case for further GS E&C gains depends on tenant confirmation and progress on a further 1GW of capacity. A ceremony forecast does not establish when main construction will begin.
For US nuclear work, Shinhan expects some lead projects to reach front-end engineering design, early works or preferred-bidder selection in 2027, rather than large-scale nuclear order bookings. It sees AI infrastructure driving shares in the first half and greater visibility on nuclear orders in the second. Its preferred construction stock is Samsung E&A for the first half of 2027 and Hyundai E&C for the second.
A separate contractual condition concerns the US government’s Westinghouse participation interest. Cameco’s October 2025 disclosure sets a January 2029 expiry unless the interest has vested. Vesting requires the government to make a final investment decision and enter definitive agreements before January 2029 for at least US$80 billion of new US Westinghouse reactor construction. The interest provides conditional rights to cash distributions, rather than an ordinary equity stake. Shinhan views the timetable and the economics of repeat reactor orders as reasons an indefinite delay is unlikely.
Policy support is distinct from project execution. Eugene expects bipartisan US backing for nuclear power to continue. Its analysts also argue that dry-cooled advanced small modular reactor designs could reduce cooling-water demand and widen site options.
What limits the valuation case?
Further valuation gains from 2028 onward depend on risk-sharing terms in nuclear engineering, procurement and construction contracts and evidence that builders can earn more than expected, according to Shinhan.
The brokerage projects 40–60% year-on-year operating-profit growth at large builders in 2027. It cites improving backlog profitability, more redevelopment projects reaching presales or construction starts, and expectations of increased shareholder returns as support for a higher share-price floor. In its earlier Nov. 3 earnings review, Hana reported stronger housing margins while warning that housing revenue could remain weak.
How have shares and housing indicators moved?
Construction stocks fell 2.3% in the week ended Nov. 6, against an 11.7% KOSPI decline, an outperformance of 9.4 percentage points, according to Hana’s Nov. 10 weekly report.
Net trading flows differed by investor group. Institutions were net buyers of Samsung C&T, Samsung E&A and GS E&C, and net sellers of Hyundai E&C and DL E&C. Foreign investors were net buyers of Hyundai E&C and net sellers of Samsung C&T and Samsung E&A.
Apartment prices rose while the sales supply-demand measure weakened. Hana reported a 0.07% weekly increase in nationwide apartment prices and a third consecutive weekly decline in the nationwide apartment sales supply-demand index, to 99.6.
Sources
- Shinhan Investment Corp. — From an across-the-board rally to a selective rally (Nov. 10, 2027 construction outlook) stock.naver.com
- Shinhan Investment Corp. — Nov. 10 construction outlook, official PDF bbs2.shinhansec.com
- Shinhan Investment Corp. — Shinhan Construction Weekly (second week of November) stock.naver.com
- Hana Securities — Blue-wave beneficiaries: Korean data centres stock.naver.com
- Eugene Investment & Securities — Infrastructure investment after the US midterm elections stock.naver.com
4 more sources
- Hana Securities — Construction Weekly: earnings, Czech nuclear plant and data-centre update stock.naver.com
- Hana Securities — Nov. 3 construction weekly, official PDF file.hanaw.com
- Hana Securities — Nov. 10 construction weekly, official PDF hanaw.com
- Cameco — Material change report dated Oct. 31, 2025: Westinghouse partnership terms sec.gov