Korean chip analysts assess profit durability and valuation downside
Hana Securities expects limited near-term earnings impact from data-centre permitting concerns. Other reports examine valuation downside and whether long-term contracts can protect profits beyond the expected peak.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-11 (KST)
Investor attention is shifting from next year’s memory earnings to how much profit can survive beyond the expected peak, according to DS Investment & Securities. Its Nov. 10 outlook examines cloud providers’ purchasing capacity and earnings sensitivity to price declines in 2028 and 2029.
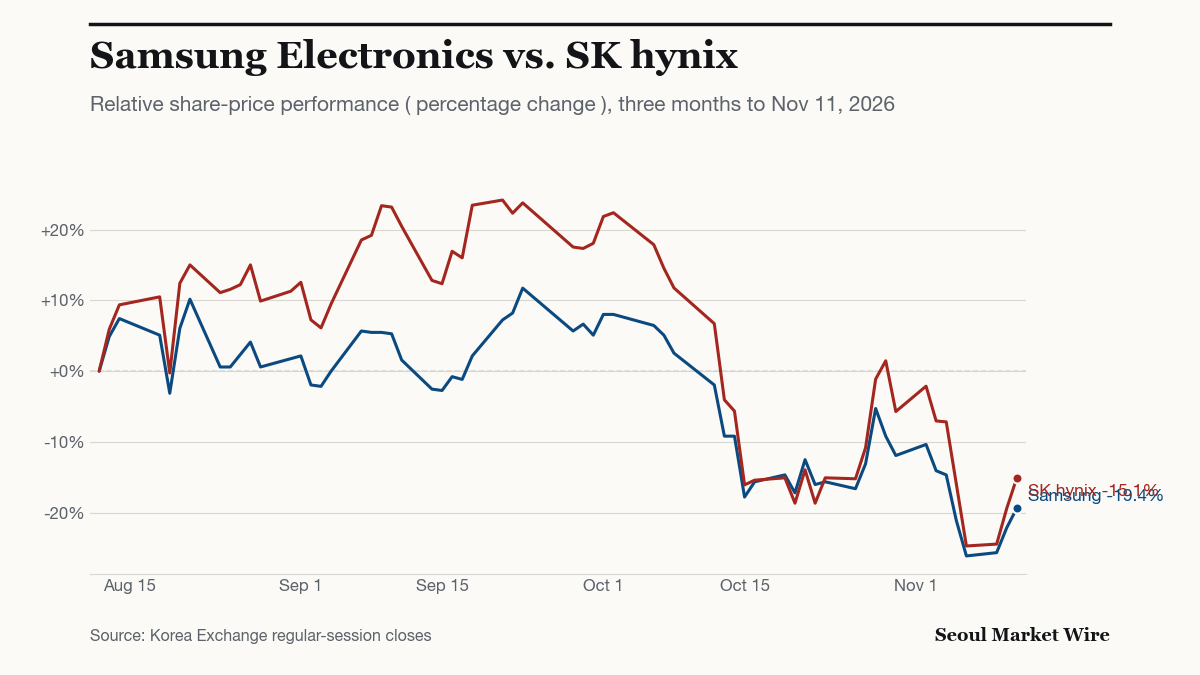
The question follows a sell-off. In its Nov. 9 review, Hana Securities recorded declines over the preceding week of 11.7% for the KOSPI, 16.1% for Samsung Electronics and 20.2% for SK hynix. The brokerage attributed the selling to concerns about future US data-centre approvals following the Democrats’ election victory.
Samsung closed at 206,000 won on Nov. 11, up 3.57%, while SK hynix gained 5.36% to 1,277,000 won.
How does Hana assess the near-term earnings impact?
Hana expects data-centre permitting concerns to have a limited near-term impact on earnings.
Reported results and exports provide a separate measure of activity. Third-quarter operating profit reached 83.3 trillion won at SK hynix and 107.4 trillion won at Samsung. Samsung’s figure covers the consolidated company, not memory alone. October semiconductor exports totalled $56.44 billion, up 259.4% year on year.
For 2027, Shinhan Securities forecasts DRAM bit supply growth of 21% and NAND growth of 23% in its Nov. 9 outlook. Its analysts expect demand to exceed supply and average selling prices to rise 40% and 31%, respectively, year on year.
What do the valuation comparisons measure?
Historical trough multiples underpin Hanwha Investment & Securities’ report, dated Nov. 6 on its official listing. Samsung’s 12-month forward price-to-book ratio (P/B) reached 0.95x in January 2019, 1.03x in September 2022 and 0.83x in November 2024. Applying 1.03x to Hanwha’s estimated 12-month forward book value of 173,079 won per share implies about 178,000 won; the average trough multiple of roughly 0.94x implies about 163,000 won. Neither establishes a floor.
In its Nov. 10 note, Daishin Securities cited 12-month forward P/B ratios of 1.14x for Samsung and 1.11x for SK hynix, calling them excessively low. Those are report valuations, not ratios calculated from the Nov. 11 closes. The brokerage retained its Buy ratings and price targets.
A different comparison uses projected 2028 high-bandwidth memory (HBM) earnings. Applying a TSMC-based price-to-earnings (P/E) multiple to those earnings, iM Securities’ Nov. 4 analysis estimated HBM values equivalent to 108% of Samsung’s and 135% of SK hynix’s market capitalisations at the time of the report. Samsung’s comparison includes ordinary and preferred shares. These are comparisons with report-time market values, not forecasts of 2028 market capitalisations.
Would long-term contracts protect profits?
Under iM’s stress-test assumptions, customers could consider cancelling long-term agreements (LTAs) after DRAM prices fell at least 60% from the projected fourth-quarter 2027 peak. In that model, such a decline would require 2027 server shipments to fall 7% year on year, compared with iM’s base-case forecast of 18% growth. The threshold is a model result, not a universal rule for customer behaviour.
What could weaken the earnings outlook?
Future approvals remain a policy risk. Hana’s Nov. 6 report linked selling to fears of tighter permitting in Texas, Georgia and Ohio. Its subsequent review distinguished projects already under way, where it saw limited risk, from pending or planned sites.
Funding and competition also feature in the research. Yuanta Securities Korea’s Nov. 2 review linked October’s declines to concerns about funding AI infrastructure as global interest rates rose. It also identified weaker free cash flow at big-tech companies as a source of renewed doubts about AI investment. Hana’s Nov. 2 review highlighted customers’ spending burden. In Kyobo Securities’ Nov. 2 analysis, Chinese memory makers’ technological progress, including advances at CXMT, posed a medium- to long-term competitive threat.
On supply, Shinhan forecasts capital spending by Samsung, SK hynix and Micron to rise more than 40% year on year in 2027. Separately, iM expects uncertainty about 2028 prices to constrain first-half 2027 valuation multiples.
Equipment suppliers suffered sharper weekly falls: Hana reported declines of more than 30% for PSK Holdings and PSK in its Nov. 9 review. The same review recorded a 45% weekly decline in CMTX following weaker-than-expected third-quarter results.
Sources
- DS Investment & Securities — 머슬 메모리 (Nov. 10) stock.naver.com
- Daishin Securities — 투자자 핵심 Q&A 3선 (Nov. 10) stock.naver.com
- Hana Securities — 악재가 적극적으로 선반영된 주가 (Nov. 9) stock.naver.com
- Hanwha Investment & Securities — 반도체 Valuation Call from Hawaii: 바닥을 판단하는 단 하나의 기준 (Nov. 6) stock.naver.com
- Hanwha Investment & Securities — Official report listing (Nov. 6 publication date) hanwhawm.com
11 more sources
- Shinhan Securities — 노이즈 캔슬링 (Nov. 9) stock.naver.com
- Hana Securities — 데이터센터 관련 과도한 우려 (Nov. 6) stock.naver.com
- iM Securities — STRESS TEST (Nov. 4) stock.naver.com
- Kyobo Securities — CXMT, 과연 위협일까? (Nov. 2) stock.naver.com
- Hana Securities — 지워지지 않는 물음표 (Nov. 2) stock.naver.com
- Yuanta Securities Korea — 2026년 11월 Preview: 괴리(乖離) (Nov. 2) stock.naver.com
- SK hynix — Third-quarter 2026 business results news.skhynix.com
- Samsung Electronics — Third-quarter 2026 results news.samsung.com
- Ministry of Trade, Industry and Resources — October 2026 exports and imports motir.go.kr
- Yahoo Finance — Samsung Electronics historical prices finance.yahoo.com
- Yahoo Finance — SK hynix historical prices finance.yahoo.com