Hana cuts Korea Investment Holdings price target by 21.7% after Q3 profit miss
The brokerage kept its Buy rating despite the earnings miss. At subsidiary Korea Investment & Securities, retail financial-product balances in a category including pensions, wrap accounts and trusts fell by about 1 trillion won.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-06 (KST)
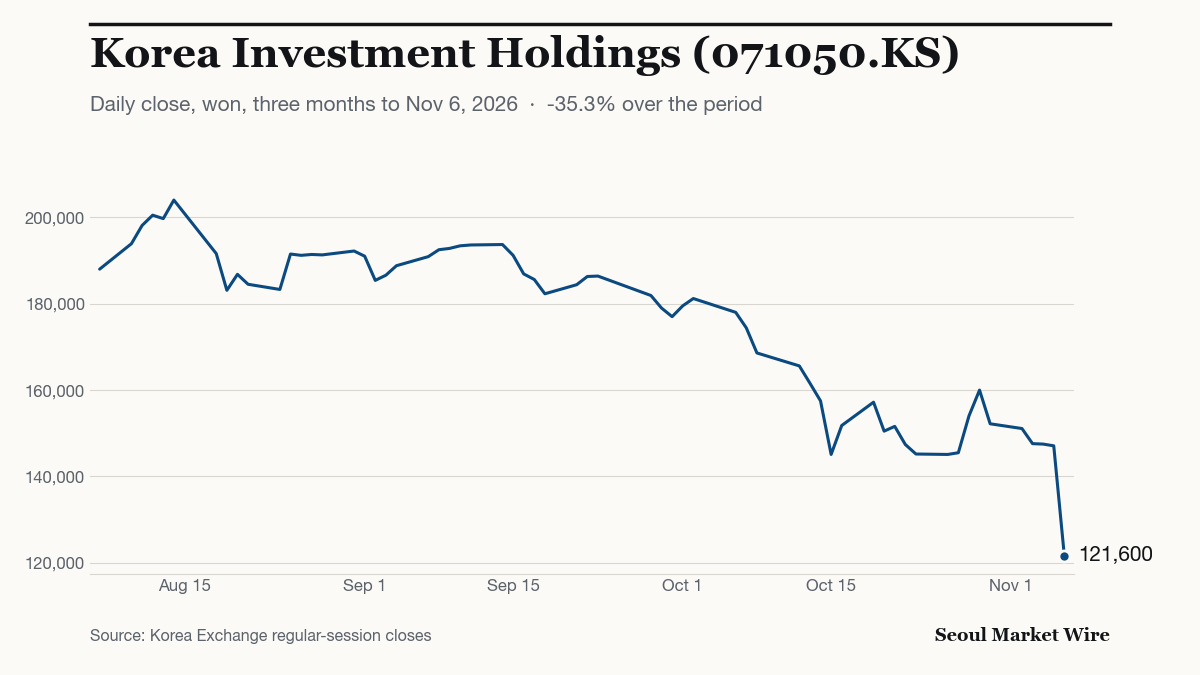
Hana Securities cut its price target for Korea Investment Holdings to 249,000 won from 318,000 won, a 21.7% reduction, after third-quarter profit missed market forecasts. The brokerage retained its Buy rating in its Nov. 6 review, citing an unfavourable market environment for the weak results.
The 21.7% reduction is calculated from the targets in Hana’s rating-history table: a 69,000 won cut from 318,000 won. The report’s narrative gives a different figure, approximately 28%. Its cover is dated Nov. 6, 2025, while its rating history and compliance notice are dated Nov. 6, 2026.
At the report’s reference price of 142,900 won, dated Nov. 5, the revised target implies 74.2% upside.
How far did results miss?
Net profit attributable to shareholders of the parent was 282.3 billion won for July–September, against the 501.4 billion won consensus cited in the review. The shortfall was 219.1 billion won, or 43.7%; that percentage measures the miss against forecasts, rather than a year-on-year decline.
Lower brokerage and wealth-management income, together with increased valuation losses on assets, were the main causes identified by Hana. At subsidiary Korea Investment & Securities, brokerage net fee income was 207.8 billion won, down 40.6% from the second quarter. Wealth-management net fee income fell 73.4% quarter on quarter to 57.5 billion won, according to the report.
What changed in retail balances?
In its discussion of the subsidiary’s wealth-management business, the review reported that balances in the “other” category of individual customers’ financial products fell by about 1 trillion won quarter on quarter in July–September. They had increased by 8 trillion won in April–June.
That category includes pensions, wrap accounts and trusts, among other products. The reported change therefore covers a broader category than those three products alone. A change in balances also does not, by itself, establish the amount of net customer withdrawals.
The balance figures relate to the quarter ended Sept. 30, before the sharp market declines on Nov. 5 and 6.
What did valuations reflect before the sell-off?
Before those declines, SK Securities argued in a Nov. 4 sector assessment that brokerage valuations already reflected lower turnover, weaker sentiment and the prospect of weaker-than-expected third-quarter earnings. The brokerage retained an Overweight sector rating.
The turnover comparison depended on both the period and the products counted. On the report’s measure combining KRX, Nextrade and ETF trading, October average daily turnover was 58.5 trillion won, up 3.0% from September but below the third-quarter average of 75.3 trillion won. Excluding the separately counted ETF category, KRX and Nextrade turnover fell 5.1% month on month to 38.1 trillion won.
Kiwoom Securities’ Nov. 6 Morning Letter recorded a 5.28% KOSPI decline to 5,383.80 on Nov. 5 and foreign net selling of about 3.40 trillion won in the KOSPI market that session.
On Nov. 6, the KOSPI fell another 6.02% to close at 5,059.69.
Sources
- Hana Securities — Korea Investment Holdings: 3Q26 review (Nov. 6, 2026) stock.naver.com
- Hana Securities — original review PDF: results and retail balances p. 1, narrative target reduction p. 2, target history p. 6. Cover dated Nov. 6, 2025; rating history and compliance notice dated Nov. 6, 2026. stock.pstatic.net
- SK Securities — October turnover and brokerage valuations (Nov. 4, 2026) stock.naver.com
- SK Securities — original sector report PDF, turnover definitions and valuation view p. 1 stock.pstatic.net
- Kiwoom Securities — Kiwoom Morning Letter (Nov. 6, 2026) stock.naver.com