Kiwoom cuts Classys target 35.2% and Mirae Asset Securities target 18.5%
Kiwoom cut its Classys target after another earnings miss and lowered its target for Mirae Asset Securities after investment losses. NAVER targets diverged, while IBK cut KEPCO's target 49.4%.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-13 (KST)
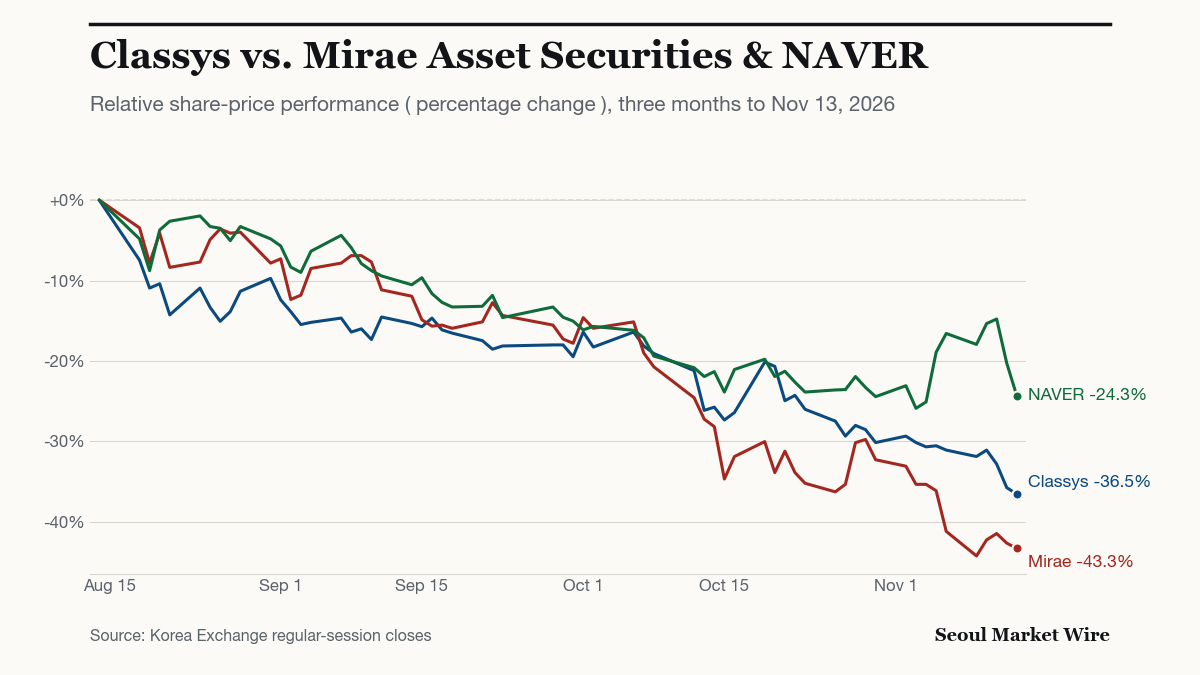
The price target for Classys fell 35.2% to 35,000 won from 54,000 won in Kiwoom Securities’ Nov. 13 report after a second consecutive quarterly earnings miss against market expectations. The brokerage retained Buy.
Its report on Mirae Asset Securities that day cut the target 18.5% to 53,000 won from 65,000 won, also retaining Buy. These are selected revisions, rather than a ranking of all cuts issued that day.
Selected price-target cuts
| Company | Brokerage | New target | Change |
|---|---|---|---|
| Classys | Kiwoom Securities | 35,000 won | -35.2% (from 54,000 won) |
| Mirae Asset Securities | Kiwoom Securities | 53,000 won | -18.5% (from 65,000 won) |
| NAVER | Mirae Asset Securities | 240,000 won | -14.3% (from 280,000 won) |
| KEPCO | IBK Investment & Securities | 39,000 won | -49.4% (from 77,000 won) |
How did earnings affect the targets?
At its second-quarter results announcement, Classys lowered its 2026 revenue guidance to 430 billion–460 billion won from 470 billion–510 billion won. The midpoint fell 9.2%, from 490 billion to 445 billion won. Kiwoom judged the revised range unlikely to be met.
For Mirae Asset Securities, Kiwoom reported third-quarter net profit on a standalone basis rose 42% year on year to 100.7 billion won. On a consolidated basis, the company recorded a net loss attributable to owners of 394.1 billion won after about 900 billion won in pre-tax investment losses. Lower earnings estimates and treasury-share disposal plans informed the target cut.
Where did NAVER targets diverge?
The Nov. 12 report from Mirae Asset Securities cut NAVER’s target to 240,000 won from 280,000 won, retaining Buy. IBK Investment & Securities’ Nov. 13 report maintained a 320,000-won target and Buy, an 80,000-won gap. The former highlighted slower advertising and commerce growth; IBK emphasized prospective earnings from NAVER’s AI factory business.
Why was KEPCO’s target cut?
Higher fuel prices and the system marginal price, a wholesale electricity-market benchmark, were among the cost pressures IBK cited in its Nov. 13 KEPCO report. Renewable portfolio standard and carbon-emission costs also weighed on its assessment. The analysts cut earnings estimates and the valuation multiple, lowering the target to 39,000 won from 77,000 won while retaining Buy.
For the third quarter, Kiwoom’s Nov. 13 report put KEPCO’s consolidated operating profit at 1.6442 trillion won, down 71% year on year. That missed its 2.899 trillion-won estimate and market expectations of 2.4143 trillion won. Electricity sales revenue was about 850 billion won below its forecast, while fuel and power-purchase costs matched its estimates.
For 2027, Kiwoom projected a 0.4% year-on-year decline in power-purchase costs, with lower purchase volumes offsetting higher renewable energy certificate costs.
NAVER investor flows on Nov. 12
On Nov. 12, foreign investors net sold 62,255 NAVER shares and institutions net sold 391,750 shares on the Korea Exchange, according to Naver Pay Securities. These figures cover KRX trading only.
Sources
- Kiwoom Securities — Classys: A lean season just as autumn ends (2026-11-13) stock.naver.com
- Kiwoom Securities — Mirae Asset Securities 3Q26 review: An expected loss; investment capability now needs proving (2026-11-13) stock.naver.com
- Mirae Asset Securities — NAVER: Concern over slowing core-business growth (2026-11-12) stock.naver.com
- IBK Investment & Securities — KEPCO: Expectations for nuclear expansion still hold (2026-11-13) stock.naver.com
- Kiwoom Securities — KEPCO: A painful fall in electricity sales volume (2026-11-13) stock.naver.com