Shinhan lifts YC price target 26.7%; Hanwha cuts Misto Holdings target 23.1%
YC and Misto Holdings had the largest percentage revisions among four comparable target changes. A separate i3system cut reflected a lower valuation multiple.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-17 (KST)
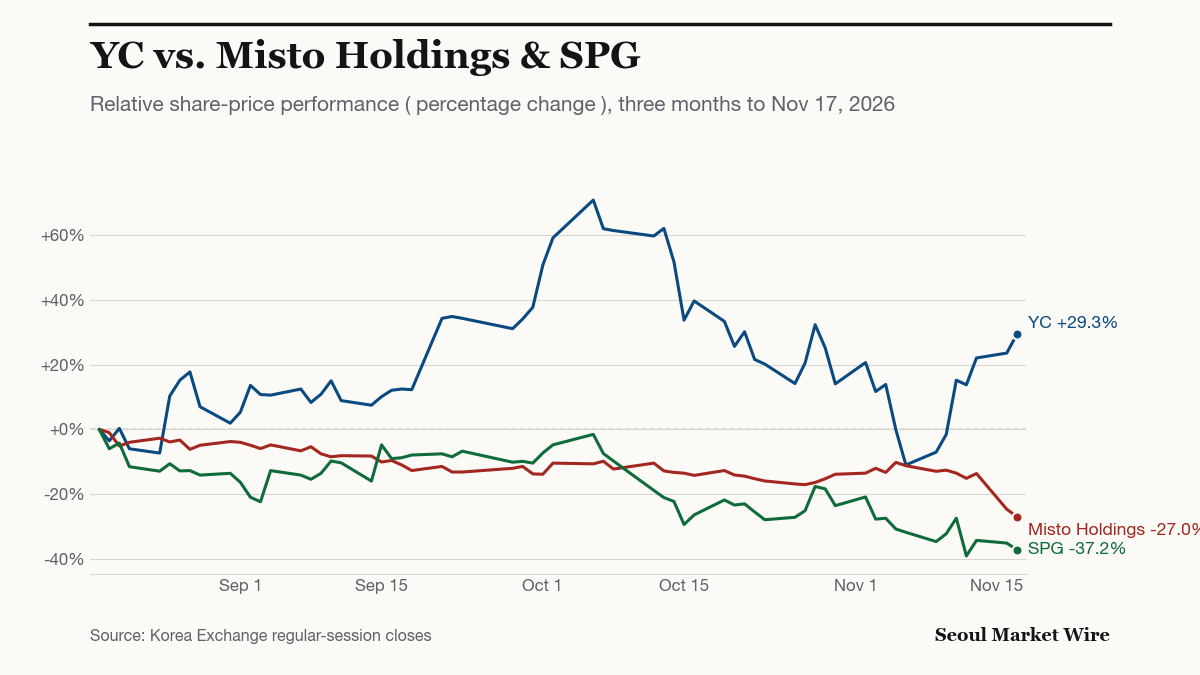
A 26.7% increase in YC’s price target on Nov. 17 was the largest percentage revision among four comparable changes in a Nov. 16–17 research digest. Shinhan Securities lifted the target to 19,000 won from 15,000 won. The largest reduction was Hanwha Investment & Securities’ Nov. 16 cut in Misto Holdings’ target to 60,000 won from 78,000 won, down 23.1%.
The selection also includes lower targets for SPG and i3system and a higher target for Hanwha Solutions. All five carried Buy ratings. The comparison covers these selected revisions, not every target change across the Korean market.
Which targets changed most?
Four revisions can be ranked by absolute percentage change because both the previous and new targets are available. Two targets rose and two fell.
| Company | Brokerage | Previous target | New target | Change |
|---|---|---|---|---|
| YC | Shinhan Securities | 15,000 won | 19,000 won | +26.7% |
| Misto Holdings | Hanwha Investment & Securities | 78,000 won | 60,000 won | -23.1% |
| SPG | Mirae Asset Securities | 129,000 won | 110,000 won | -14.7% |
| Hanwha Solutions | Mirae Asset Securities | 33,000 won | 35,000 won | +6.1% |
Each percentage is the new target minus the previous target, divided by the previous target and multiplied by 100. Figures are rounded to one decimal place. YC’s 4,000-won increase therefore ranks above Misto Holdings’ 18,000-won reduction in percentage terms, despite being smaller in won.
These percentages measure changes in analysts’ targets, not share-price returns or upside from the latest close. The retained Buy ratings are a separate measure: Misto Holdings and SPG kept that recommendation despite receiving lower targets.
What accompanies the largest revisions?
YC’s Nov. 17 report presents a changed growth trajectory alongside the higher target and retained Buy rating. The available research extract does not identify the earnings assumptions or valuation inputs responsible for the increase.
For Misto Holdings, the Nov. 16 third-quarter review pairs a forecast revenue turnaround in 2027 with a lower target. That forecast describes the brokerage’s operating outlook; it does not establish why the target was reduced.
The two revisions therefore support a comparison of direction and magnitude, but not a conclusion that one reflects higher earnings estimates and the other a lower valuation multiple.
What accompanies the SPG cut and solar upgrade?
For SPG, Mirae Asset Securities’ Nov. 17 report identifies an adverse currency effect while maintaining that growth drivers remain intact. Its target fell by 19,000 won to 110,000 won, a 14.7% reduction, with Buy retained.
Higher utilisation at Korean plants is the basis for an expected profitability improvement in the brokerage’s Hanwha Solutions research entry. The target rose by 2,000 won to 35,000 won, or 6.1%.
Its analysts also linked rising US electricity demand, particularly from data centres, to higher power purchase agreement prices. They expected those prices to improve the sale value and profitability of development assets. Those benefits are forecasts, not gains reported as already realised by the company.
Why is i3system outside the percentage ranking?
The previous target for i3system is unavailable in the supporting data, so its reduction cannot be ranked alongside the other four changes.
In its Nov. 17 report, IBK Securities lowered the target to 74,000 won and retained Buy. The brokerage cited lower market valuations in reducing its target price-to-earnings multiple to 24.8 times from 29.8 times.
That is a 16.8% reduction in the valuation multiple. It is not the percentage reduction in the price target: calculating that change requires the previous target, which cannot be inferred from the two multiples alone.
What to watch next
The following factors come from the research discussed above. The available material does not establish dates for the companies’ next earnings releases or other scheduled catalysts; Misto Holdings’ 2027 turnaround forecast is an outlook period, not an event date.
| Company / KRX ticker | Key sensitivity | Next catalyst & date |
|---|---|---|
| YC — 232140.KQ | Growth assumptions behind the higher target | No dated catalyst confirmed |
| Misto Holdings — 081660.KS | Forecast revenue turnaround in 2027 | No release date confirmed |
| SPG — 058610.KQ | Currency effects and retained growth expectations | No dated catalyst confirmed |
| Hanwha Solutions — 009830.KS | Korean plant utilisation and development-asset profitability | No dated catalyst confirmed |
| i3system — 214430.KQ | Valuation assumptions following the target P/E cut | No dated catalyst confirmed |
Sources
- Shinhan Securities: A changed growth trajectory (YC), Nov. 17, 2026 stock.naver.com
- Hanwha Investment & Securities: 3Q26 review (Misto Holdings), Nov. 16, 2026 stock.naver.com
- Mirae Asset Securities: Currency drag, growth drivers intact (SPG) stock.naver.com
- Mirae Asset Securities: Higher Korean plant utilisation to lift profitability (Hanwha Solutions) stock.naver.com
- IBK Securities: Uncooled-sensor prospects add to defence growth (i3system), Nov. 17, 2026 stock.naver.com