DS cuts EcoPro BM target 36%; Shinhan lowers its target to 120,000 won
DS and Shinhan retained buy ratings on EcoPro BM while cutting their targets, but differ on whether EcoPro BM will remain profitable at the operating level in the fourth quarter. DS also lowered its targets for L&F and Lotte Energy Materials.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-06 (KST)
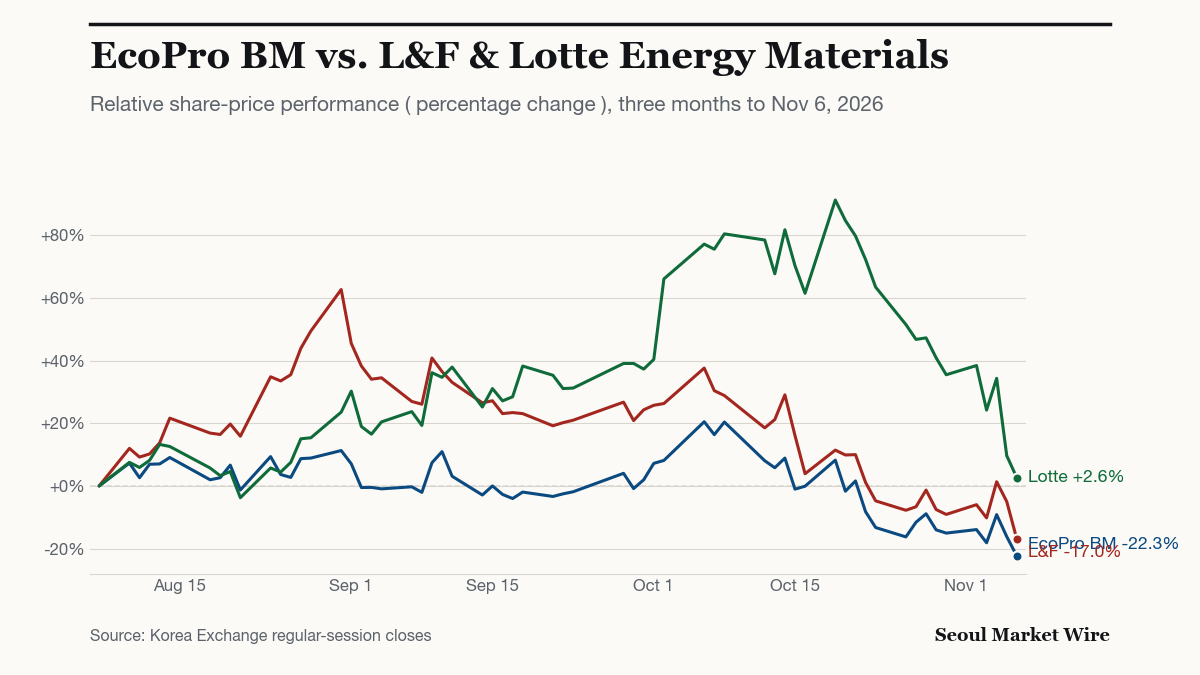
EcoPro BM drew target-price cuts of 36% and 25% on Nov. 6, but the brokerages split on whether EcoPro BM will remain profitable at the operating level in the fourth quarter. DS Investment & Securities lowered its target from 250,000 won to 160,000 won, while Shinhan Securities cut its target from 160,000 won to 120,000 won. Both retained buy ratings.
The same day’s DS reports lowered the targets for L&F by 14.3% to 300,000 won and Lotte Energy Materials by 5.4% to 70,000 won, also retaining buy ratings.
At the Nov. 6 close in Seoul, the KOSDAQ fell 5.03% to 644.27 and the KOSPI dropped 6.02% to 5,059.69. LG Energy Solution lost 2.46% to 337,500 won.
What hit third-quarter earnings?
EcoPro BM’s provisional operating profit fell to 12.0 billion won, down 33.3% from the second quarter and 76.2% from a year earlier. DS attributed the decline to stalled North American EV demand and European carmakers’ model changes. The brokerage described a September production halt during preparations to start the second Hungarian line, attributing it to a safety-authority inspection and citing added fixed costs.
For L&F, the provisional operating loss of 26.5 billion won marked a reversal from profits both a year earlier and in the previous quarter. Sales were 874.4 billion won. DS identified a 42.6 billion won lithium-inventory write-down and 22 billion won in currency-related losses as the main causes. Mid-nickel cathode shipments also fell 32% quarter on quarter as European EV demand slowed.
At copper-foil maker Lotte Energy Materials, the operating loss was 21.3 billion won. Its fifth Malaysian plant added ramp-up costs, with new-plant fixed costs running at 10 billion to 12 billion won a quarter, according to DS.
How do the EcoPro BM forecasts compare?
Fourth-quarter operating profit is forecast at 5.0 billion won by DS, against a 9.7 billion won operating loss at Shinhan. Both expect costs from the Hungarian shutdown to weigh on earnings. DS expects inventory-provision reversals and cost controls to partly offset the shutdown costs.
The cut to 160,000 won reflects DS’s reduced 2027 estimate for earnings before interest, tax, depreciation and amortisation. Its analysts expect some Hungarian output to replace shipments previously produced in Pohang, limiting the increase in company-wide volumes. They identified new orders as a potential source of earnings upgrades.
The 120,000 won target incorporates Shinhan’s reduced earnings estimates and the rights offering. Its analysts judged near-term weakness and dilution concerns largely reflected in the share price, while identifying normal Hungarian operations and new customers as conditions for recovery. Both reports list EcoPro BM’s Nov. 5 closing price as 89,700 won on their cover pages.
What supports recovery at L&F and Lotte?
A fourth-quarter return to operating profit at L&F would still leave thin margins. DS forecasts reported operating profit of 3.4 billion won, a margin of about 0.4%. It puts the recurring margin in the 1% range. Selling prices are expected to fall 3% as lithium procurement prices decline, with lagged currency effects also weighing. The brokerage expects most inventory-related earnings volatility to subside after the first half of 2027.
For 2027, DS expects cathode materials for 46-series cylindrical cells to account for up to 40% of L&F’s nickel-cobalt-manganese (NCM) shipments. The brokerage expects L&F to remain the sole cathode supplier to its main customer in the fourth quarter, while identifying dual sourcing as a risk. It also cites lithium iron phosphate (LFP) cathode orders totalling 250,000 tonnes, equivalent to 100GWh of energy storage system (ESS) batteries.
At Lotte, DS forecasts another operating loss of 21.0 billion won in the fourth quarter. Although the report’s headline refers to a second-half 2027 turnaround, its detailed forecast places the return to consolidated operating profit in the second quarter, with stronger profitability from the second half. The brokerage said battery-foil processing-fee increases had been agreed with some customers in the third quarter; remaining negotiations were expected to conclude in the fourth.
What supports Korean cell makers’ grid-storage growth?
In a separate Nov. 6 report, Hana Securities examined demand for ESS batteries made by Korean cell manufacturers. It argued that US data-centre construction delays would have little effect on their ESS growth, attributing orders to replacing Chinese suppliers in an established US grid-storage market averaging about 70GWh a year. The report linked US utilities’ orders to subsidy and tariff requirements favouring supply chains outside China and Korean manufacturers with US production.
Sources
- DS Investment & Securities: EcoPro BM, after the reset in expectations, focus on order confirmation (Nov. 6, 2026) stock.naver.com
- Shinhan Securities: EcoPro BM, Hungary ramp-up marks the start of recovery (Nov. 6, 2026) stock.naver.com
- DS Investment & Securities: L&F, look past the one-off loss to 100GWh of LFP orders (Nov. 6, 2026) stock.naver.com
- DS Investment & Securities: Lotte Energy Materials, processing-fee increase confirmed, profit turnaround in 2H27 (Nov. 6, 2026) stock.naver.com
- Hana Securities: The case for battery gains from the US midterms needs refining (Nov. 6, 2026) stock.naver.com