Lithium write-down pushes L&F to Q3 loss; Hana holds 140,000-won target
Hana Securities puts L&F's operating profit excluding the inventory valuation loss at 16.1 billion won. NCM cathode shipments fell, and the brokerage forecasts another operating loss in the fourth quarter.
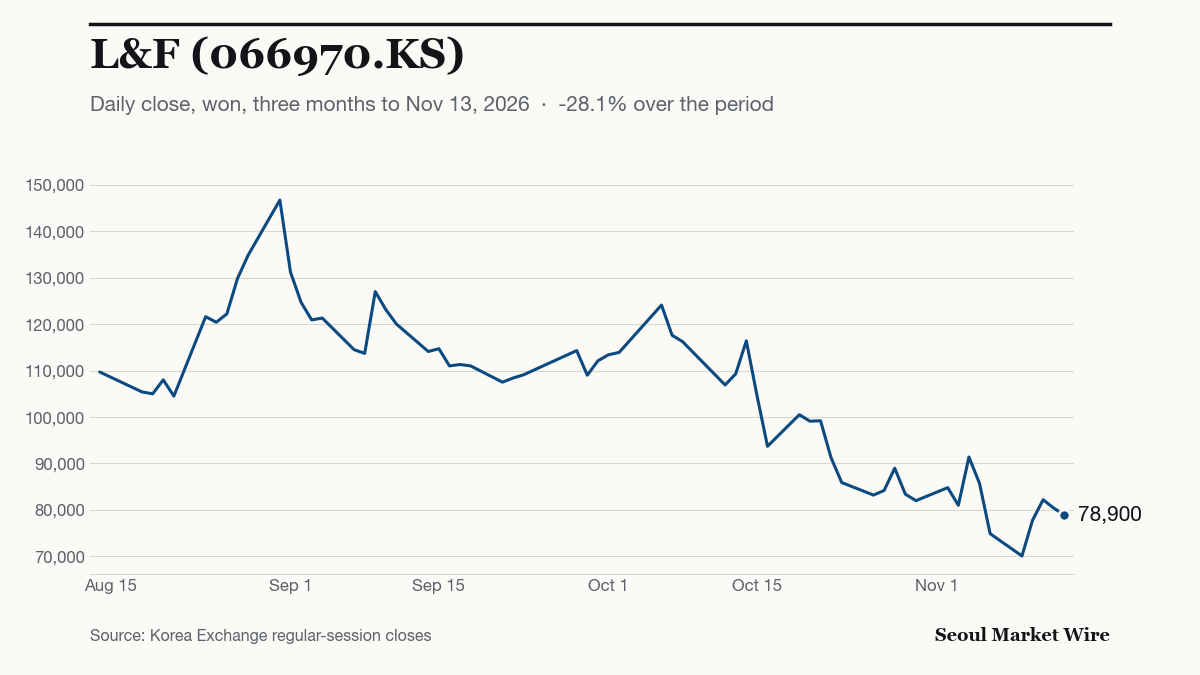
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-13 (KST)
Battery-materials maker L&F posted a third-quarter operating loss after an inventory write-down. Hana Securities retained its Buy rating and 140,000-won price target in its Nov. 13 report, calculating that operating profit remained positive when the inventory valuation loss is excluded, even as NCM cathode shipments declined.
Third-quarter sales rose 34% from a year earlier to 874.4 billion won, according to the report. The company recorded an operating loss of 26.5 billion won.
What drove the operating loss?
Lower lithium prices resulted in a 42.6 billion won inventory valuation loss, Hana reported. A stronger won also had an adverse impact of 22 billion won on operating earnings.
Excluding only the inventory valuation loss, the brokerage calculates operating profit of 16.1 billion won. The currency impact remains included. On a basis excluding inventory-related gains and losses, its analysts count four consecutive quarters of operating profit.
Which products slowed?
High-nickel cathode shipments rose 3% from the second quarter, according to Hana.
Mid-nickel shipments fell 32% over the same period. The brokerage attributed that decline to Korean cell makers’ continued weakness in Europe’s electric-vehicle battery market. Total nickel-cobalt-manganese (NCM) cathode shipments fell 5% quarter on quarter.
What supports the 2027 shipment forecasts?
Initial deliveries of lithium iron phosphate (LFP) cathode material began in late third-quarter 2026, according to the report. For 2027, Hana forecasts LFP shipments of 40,000 metric tons for North American energy-storage systems, with a reported order backlog of about 250,000 metric tons. Its analysts link that demand to AI data centres.
For Rivian-related NCM95 high-nickel cathode material, the brokerage forecasts shipments of 14,200 metric tons in 2027, compared with an estimated 7,600 metric tons in 2026.
Does Hana expect a fourth-quarter profit?
The brokerage forecasts fourth-quarter sales of 873.3 billion won, roughly unchanged from the third quarter, and an operating loss of 25.4 billion won. Lower selling prices tied to raw-material costs and further inventory valuation losses feature in that forecast.
The unchanged 140,000-won price target compares with a Nov. 12 share price of 80,400 won cited in the report.