KAI's Q4 sales growth faces Iraq provisions and development spending
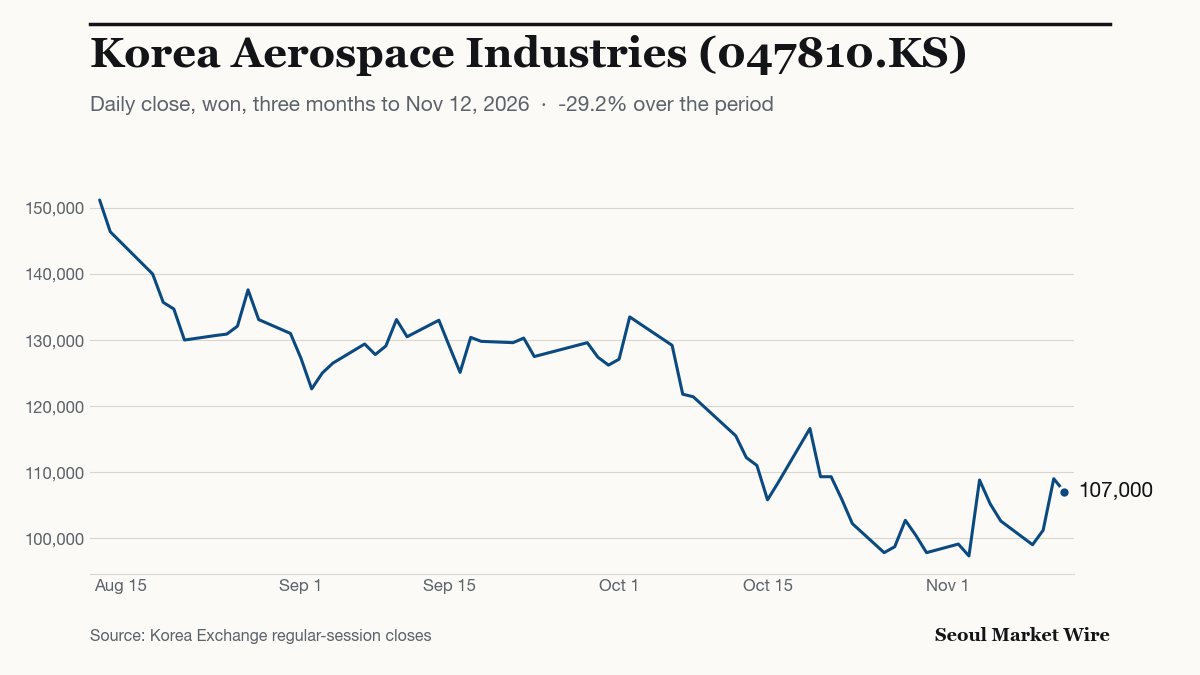
Yuanta expects higher fourth-quarter sales but identifies risks to profitability. Ten Nov. 4 target-price entries average 162,000 won, against the Nov. 12 close of 107,000 won.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-12 (KST)
Yuanta Securities Korea’s Nov. 4 forecast calls for higher fourth-quarter revenue at Korea Aerospace Industries, but identifies additional Iraq provisions and development spending as risks to profitability.
The forecast assumes delivery of at least six KF-21 fighters to the Korean military, compared with two in Q3, and two or three LAH light armed helicopters. It also assumes higher revenue from FA-50 projects in Malaysia, Poland and the Philippines as work progresses. The LAH estimate represents a limited resumption after delivery delays.
The brokerage estimates in-house development spending of up to 100 billion won in Q4, compared with 60 billion won in January–September. The available report summary does not specify how much of that spending would be expensed in Q4.
What does the ten-report sample show?
KAI’s preliminary third-quarter revenue was 1.0643 trillion won, up 51.6% from a year earlier, while operating profit rose 31.9% to 79.4 billion won. The operating margin was about 7.5%, according to Eugene Investment & Securities’ Nov. 4 review.
The table uses Naver Pay Securities research entries compiled in the Nov. 13 factsheet for this article. It selects the latest entry for each of ten brokerages in the supplied 180-day dataset; all ten are dated Nov. 4. This sample is not a market-wide consensus.
Their targets average 162,000 won, with a median of 161,500 won and a range of 135,000–186,000 won. The average is 51.4% above the Nov. 12 close of 107,000 won, when KAI fell 1.83%, according to company IR data.
Nine entries display Buy ratings. SK Securities’ rating field is blank in the supplied data; that does not establish that its report contained no recommendation.
| Brokerage | Report date | Rating in source data | Target price |
|---|---|---|---|
| DS Investment & Securities | Nov. 4, 2026 | Buy | 186,000 won |
| Kiwoom Securities | Nov. 4, 2026 | Buy | 185,000 won |
| Yuanta Securities Korea | Nov. 4, 2026 | Buy | 182,000 won |
| Daishin Securities | Nov. 4, 2026 | Buy | 173,000 won |
| Mirae Asset Securities | Nov. 4, 2026 | Buy | 173,000 won |
| Hanwha Investment & Securities | Nov. 4, 2026 | Buy | 150,000 won |
| SK Securities | Nov. 4, 2026 | Not displayed | 150,000 won |
| Eugene Investment & Securities | Nov. 4, 2026 | Buy | 146,000 won |
| Shinhan Securities | Nov. 4, 2026 | Buy | 140,000 won |
| iM Securities | Nov. 4, 2026 | Buy | 135,000 won |
What was operating profit after the specified adjustments?
Estimates of the currency benefit differ. A stronger won reduced estimated export-contract costs, producing an operating-profit benefit of about 40 billion won in Eugene’s calculation, versus 30 billion won in Yuanta’s. Eugene also identifies about 30 billion won of one-off charges, including 12 billion won for Iraq receivables.
Separately, Shinhan Securities’ Nov. 4 analysis estimates adjusted Q3 operating profit of 69.4 billion won after excluding currency effects and one-off costs, 8.7% below its cited consensus.
The stronger won had a different effect on aerostructures profitability. Hanwha Investment & Securities’ Nov. 4 review attributes part of the 1.1-percentage-point year-on-year decline in KAI’s consolidated operating margin to weaker profitability in that business.
For Q4, Eugene sees operating profit potentially exceeding 100 billion won if no additional provisions arise.
What price underlies the earnings multiple?
At its reference share price of 97,300 won, Eugene put KAI at 24.2 times consensus 12-month forward earnings, below its historical average of 26.5 times. Those multiples do not describe the valuation at the Nov. 12 close.
How much of the order target remained?
Third-quarter orders totalled 1.5806 trillion won, according to Mirae Asset Securities’ Nov. 4 review. Most came from aircraft exports; the review says the customer country and aircraft type were not disclosed.
Eugene estimated that about 8.2 trillion won remained to meet the 10.4 trillion won annual order target. Assuming KAI secures about 3 trillion won from a third LAH production batch and 0.4 trillion won from aerostructures work, the brokerage calculates that another 4.8 trillion won would be needed from aircraft exports and other orders.
Sources
- Yuanta Securities Korea — Nov. 4, 2026: Q3 review, Q4 sales and spending risks stock.naver.com
- Eugene Investment & Securities — Nov. 4, 2026: Q3 review, orders and valuation stock.naver.com
- Eugene Investment & Securities — official Nov. 4, 2026 report eugenefn.com
- Daishin Securities — Nov. 4, 2026 research and target-price entry stock.naver.com
- Shinhan Securities — Nov. 4, 2026: deliveries, orders and adjusted profit stock.naver.com
7 more sources
- Hanwha Investment & Securities — Nov. 4, 2026: Q3 review and margin analysis stock.naver.com
- DS Investment & Securities — Nov. 4, 2026 research and target-price entry stock.naver.com
- Kiwoom Securities — Nov. 4, 2026 research and target-price entry stock.naver.com
- Mirae Asset Securities — Nov. 4, 2026: Q3 results and orders stock.naver.com
- SK Securities — Nov. 4, 2026 research and target-price entry stock.naver.com
- iM Securities — Nov. 4, 2026 research and target-price entry stock.naver.com
- Korea Aerospace Industries IR — daily share prices, Nov. 12, 2026 close ir.gsifn.io