KAI's 2026 sales forecast to miss original guidance on LAH delays, SK says
SK Securities puts 2026 sales at about 5.2 trillion won as helicopter deliveries slip. Other reports forecast higher fourth-quarter revenue from KF-21 deliveries and progress on export contracts.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-12 (KST)
Korea Aerospace Industries (KAI) will fall short of its original 2026 sales guidance of about 5.7 trillion won as engine problems delay light armed helicopter (LAH) deliveries, SK Securities forecast in its Nov. 4 report. The brokerage estimates sales of about 5.2 trillion won and expects deliveries of roughly 20 LAHs to be deferred to 2027. It maintained Buy while cutting its target to 150,000 won from 190,000 won.
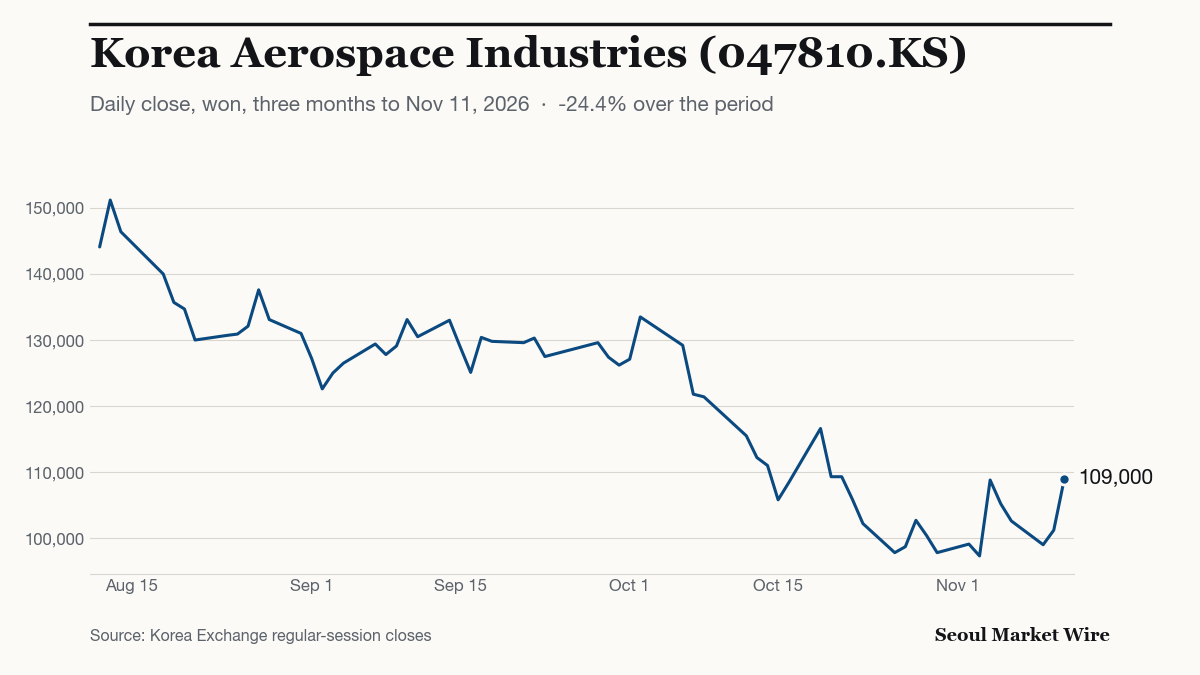
The comparison is with the original annual target. Yuanta Securities Korea’s Nov. 4 report also described a sales-guidance reduction of about 500 billion won linked to LAH delays. KAI shares closed at 107,000 won on Nov. 12, down 1.83%.
How many helicopter deliveries could slip?
The original LAH delivery plan covered 30 units in 2026. Seven were delivered in the first half, according to iM Securities’ Nov. 4 report, which forecast only two or three additional deliveries by year-end. Those figures imply a shortfall of 20 or 21 helicopters against the plan; the expectation of deferral to 2027 is SK’s forecast.
Kiwoom Securities’ Nov. 4 report expected LAH deliveries to resume in November. iM’s report that day described deliveries as having resumed. These are brokerage accounts; the materials reviewed for this article contain no separate company or military confirmation of the restart date or subsequent delivery count.
Other programmes could lift fourth-quarter revenue. Yuanta forecast at least six KF-21 deliveries, compared with two in the third quarter, alongside higher revenue recognised as Malaysian, Polish and Philippine FA-50 contracts progress. Its analysts forecast KAI’s highest quarterly revenue to date.
For the Polish FA-50PL programme alone, DS Investment & Securities projected more than 150 billion won of fourth-quarter revenue in its Nov. 4 report. The forecast concerns revenue recognition on the contract and does not specify aircraft handovers.
What do the 10 brokerage reports show?
The target prices in the 10 reports dated Nov. 4 average 162,000 won, with a median of 161,500 won. This calculation uses one target per brokerage from the selected reports, rather than a market-wide consensus. The average exceeds the Nov. 12 closing price by 51.4%. This is a comparison of the selected targets with the closing price.
| Brokerage | Date | Rating | Target Price |
|---|---|---|---|
| DS Investment & Securities | Nov. 4 | Buy | 186,000 won |
| Kiwoom Securities | Nov. 4 | Buy | 185,000 won |
| Yuanta Securities Korea | Nov. 4 | Buy | 182,000 won |
| Daishin Securities | Nov. 4 | Buy | 173,000 won |
| Mirae Asset Securities | Nov. 4 | Buy | 173,000 won |
| Hanwha Investment & Securities | Nov. 4 | Buy | 150,000 won |
| SK Securities | Nov. 4 | Buy | 150,000 won |
| Eugene Investment & Securities | Nov. 4 | Buy | 146,000 won |
| Shinhan Securities | Nov. 4 | Buy | 140,000 won |
| iM Securities | Nov. 4 | Buy | 135,000 won |
The reports also distinguish reported operating profit from earnings adjusted for currency effects and one-off costs. KAI’s third-quarter revenue was 1.0643 trillion won, up 51.6% from a year earlier, and operating profit was 79.4 billion won, up 31.9%. Its consolidated operating margin was 7.5%, down 1.1 percentage points.
Reported operating profit exceeded the consensus figures cited by Kiwoom, DS and Eugene Investment & Securities in their Nov. 4 reports. On an adjusted basis, Shinhan Securities calculated operating profit of 69.4 billion won, 8.7% below the consensus figure it cited in its report that day. The adjustment removes a 40 billion won currency-related gain and adds back 30 billion won of one-off costs.
What are the cost and valuation risks?
Higher deliveries do not remove the risk of further charges. Yuanta identified additional bad-debt provisions on the Iraq programme and fourth-quarter in-house development spending of up to 100 billion won as potential constraints on profit.
Valuation depends on earnings assumptions. Daishin Securities’ Nov. 4 report put KAI’s 36-month forward price-to-earnings ratio at 20.3 times against a global peer average of 18.0. Its analysts argued that a first KF-21 export contract in the fourth quarter could ease that valuation burden. These multiples describe the report’s comparison, rather than valuations at the Nov. 12 close.
Currency movements affected business lines differently. In its Nov. 4 report, Hanwha Investment & Securities attributed weaker aerostructures profitability partly to the stronger won, while identifying about 40 billion won of gains from exchange-rate-related revisions to estimated costs.
Sources
- iM Securities — 3Q26: The start of a recovery in defence orders?, Nov. 4, p. 1 stock.naver.com
- SK Securities — Growth in 2027–28 intact, year-end order momentum expected, Nov. 4, p. 1 stock.naver.com
- Eugene Investment & Securities — Everything has bottomed out, Nov. 4, p. 1 stock.naver.com
- Yuanta Securities Korea — 3Q26 review: earnings and orders both surprise, Nov. 4, p. 1 stock.naver.com
- Yuanta Securities Korea — Original report PDF stock.pstatic.net
9 more sources
- Shinhan Securities — Time to prove it with deliveries and orders, Nov. 4, p. 1 stock.naver.com
- Shinhan Securities — Original report PDF stock.pstatic.net
- Kiwoom Securities — Fourth-quarter orders are key, Nov. 4, p. 1 stock.naver.com
- Daishin Securities — 3Q26 review: domestic and export production revenue, Nov. 4, p. 1 stock.naver.com
- Daishin Securities — Original report PDF stock.pstatic.net
- Hanwha Investment & Securities — 3Q26 review: earnings meet expectations, Nov. 4, p. 1 stock.naver.com
- DS Investment & Securities — Confidence behind the order target, Nov. 4, p. 1 stock.naver.com
- Mirae Asset Securities — Progress in earnings and orders, Nov. 4, p. 1 stock.naver.com
- KAI investor relations — Daily share prices ir.gsifn.io