KAI brokers retain Buy ratings despite cuts and third-quarter order gap
Ten Nov. 4 brokerage reports put KAI targets at 135,000–186,000 won. Buy ratings remained intact, but order bookings and delayed helicopter deliveries complicate the fourth quarter.
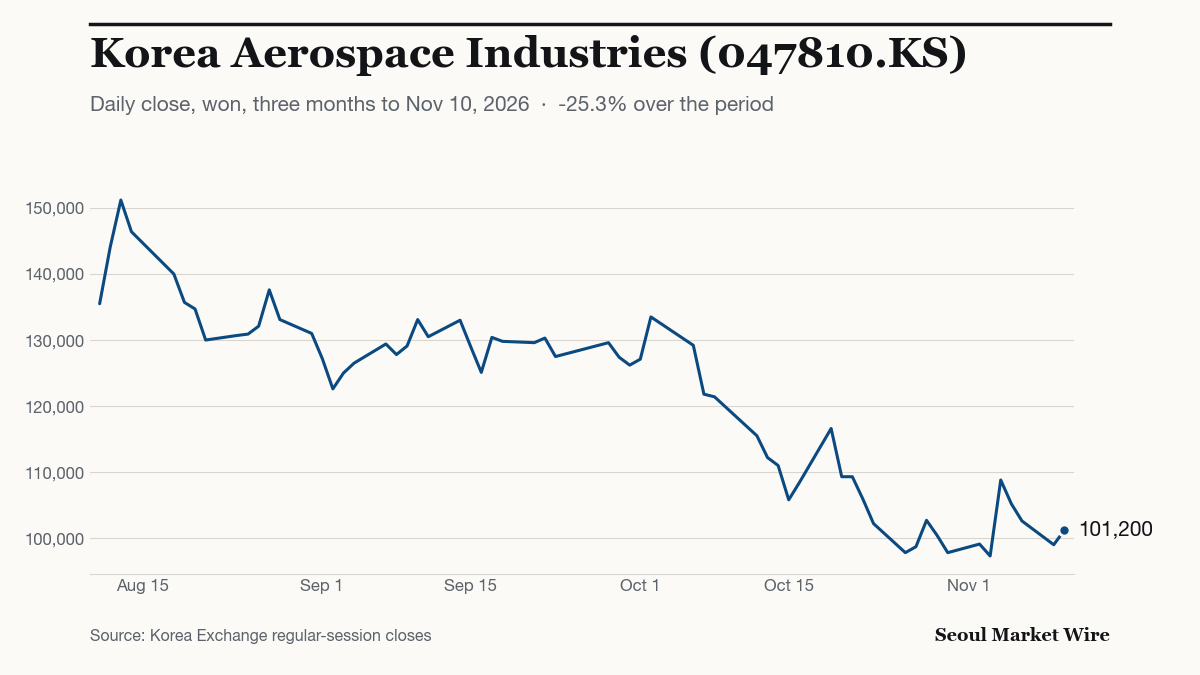
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-10 (KST)
SK Securities retained its Buy rating on Korea Aerospace Industries (KAI) in its Nov. 4 report, while cutting its price target by 21.1% to 150,000 won from 190,000 won. The brokerage pointed to delivery growth in 2027–2028 and prospective year-end orders.
The near-term hurdle is the order target. Based on bookings through the third quarter, Eugene Investment & Securities estimated in its Nov. 4 report that KAI was about 8.2 trillion won short of its 10.4 trillion won annual goal. That represents roughly 79% of the target, rather than an updated shortfall as of Nov. 10.
Shares closed at 101,200 won on Nov. 10, up 2.22%.
What do the sampled targets show?
This review covers the ten Nov. 4 KAI reports included in the research dataset supplied for this article. It does not claim to cover every report published that day. All ten carry Buy ratings, with targets ranging from 135,000 to 186,000 won.
The sample’s mean target of 162,000 won implies 60.1% upside from the Nov. 10 close. Its median target of 161,500 won implies 59.6%. These are sample statistics, not a market-wide consensus.
| Brokerage | Date | Rating | Target Price |
|---|---|---|---|
| DS Investment & Securities | Nov. 4 | Buy | 186,000 won |
| Kiwoom Securities | Nov. 4 | Buy | 185,000 won |
| Yuanta Securities Korea | Nov. 4 | Buy | 182,000 won |
| Daishin Securities | Nov. 4 | Buy | 173,000 won |
| Mirae Asset Securities | Nov. 4 | Buy | 173,000 won |
| Hanwha Investment & Securities | Nov. 4 | Buy | 150,000 won |
| SK Securities | Nov. 4 | Buy | 150,000 won |
| Eugene Investment & Securities | Nov. 4 | Buy | 146,000 won |
| Shinhan Securities | Nov. 4 | Buy | 140,000 won |
| iM Securities | Nov. 4 | Buy | 135,000 won |
Target levels and revisions tell different stories. Eugene’s report described its 146,000 won target as unchanged. By contrast, iM Securities cut its target to 135,000 won in its Nov. 4 report, citing lower valuations at its benchmark companies.
Do valuation benchmarks tell the same story?
The reports used different earnings horizons. Eugene put KAI at 24.2 times consensus 12-month forward earnings.
On a 36-month forward basis, Daishin Securities calculated 20.3 times earnings for KAI against a global peer average of 18.0 times in its Nov. 4 report. Its target valuation used projected 2028 profit attributable to controlling shareholders. These report-date ratios use different earnings periods and are not calculations based on the Nov. 10 close.
What could limit fourth-quarter earnings?
Third-quarter revenue rose 51.6% year on year to 1.0643 trillion won, while operating profit increased 31.9% from a year earlier to 79.4 billion won. The operating margin was about 7.5%. According to SK, exchange-rate adjustments to estimated costs added about 40 billion won to operating profit, while one-off provisions reduced it by about 30 billion won.
Orders and deliveries present separate challenges. In Eugene’s breakdown of the third-quarter-based order gap, a third production contract for light armed helicopters (LAH) accounted for about 3 trillion won and remaining airframe work for about 0.4 trillion won. That left about 4.8 trillion won to be filled by aircraft exports and other deals. These were prospective orders, not signed contracts closing the gap.
For deliveries, iM projected a shortfall of about 20 LAH against the annual plan of 30. Seven were delivered in the first half; following a November restart, its analysts expected only two to three more by year-end.
The brokerage’s narrative projected annual revenue 400–500 billion won below KAI’s 5.7 trillion won guidance. However, its detailed annual forecast of 5.0763 trillion won implies a larger shortfall of 623.7 billion won. The prose and table therefore give different estimates of the revenue shortfall. Its analysts assessed that the engine defect appeared not to be attributable to KAI and did not expect late-delivery penalties.
Costs could also limit the benefit of higher deliveries. Yuanta Securities Korea identified further provisions on Iraqi receivables and in-house development spending as risks in its Nov. 4 report. It put that spending at up to 100 billion won in the fourth quarter, compared with 60 billion won in the first nine months.
Sources
- Eugene Investment & Securities — Korea Aerospace Industries: Everything has bottomed out (Nov. 4, 2026) stock.naver.com
- Mirae Asset Securities — Korea Aerospace Industries: Potential confirmed in earnings and orders (Nov. 4, 2026) stock.naver.com
- Yuanta Securities Korea — Korea Aerospace Industries 3Q26 review: Surprises in both earnings and orders (Nov. 4, 2026) stock.naver.com
- Daishin Securities — Korea Aerospace Industries 3Q26 review: Domestic and export production revenue ramps up (Nov. 4, 2026) stock.naver.com
- iM Securities — Korea Aerospace Industries 3Q26: A prelude to renewed defence orders? (Nov. 4, 2026) stock.naver.com
8 more sources
- Kiwoom Securities — Korea Aerospace Industries: Fourth-quarter orders are key (Nov. 4, 2026) stock.naver.com
- Hanwha Investment & Securities — Korea Aerospace Industries 3Q26 review (Nov. 4, 2026) stock.naver.com
- DS Investment & Securities — Korea Aerospace Industries: Order guidance (Nov. 4, 2026) stock.naver.com
- Shinhan Securities — Korea Aerospace Industries: Deliveries and orders (Nov. 4, 2026) stock.naver.com
- SK Securities — Korea Aerospace Industries: Growth in 2027–2028 and year-end orders (Nov. 4, 2026) stock.naver.com
- SK Securities — Analyst's official distribution channel: KAI Buy rating and target cut t.me
- iM Securities — Official KAI research post (Nov. 4, 2026) imfnsec.tistory.com
- Korea Aerospace Industries IR — Daily share prices ir.gsifn.io