KAI's adjusted Q3 profit misses consensus, Shinhan says; broker targets differ
Ten brokerage reports published on Nov. 4 rate KAI Buy, but currency-benefit estimates and valuations differ. Eugene estimates KAI needs another 8.2 trillion won in orders to meet its annual target.
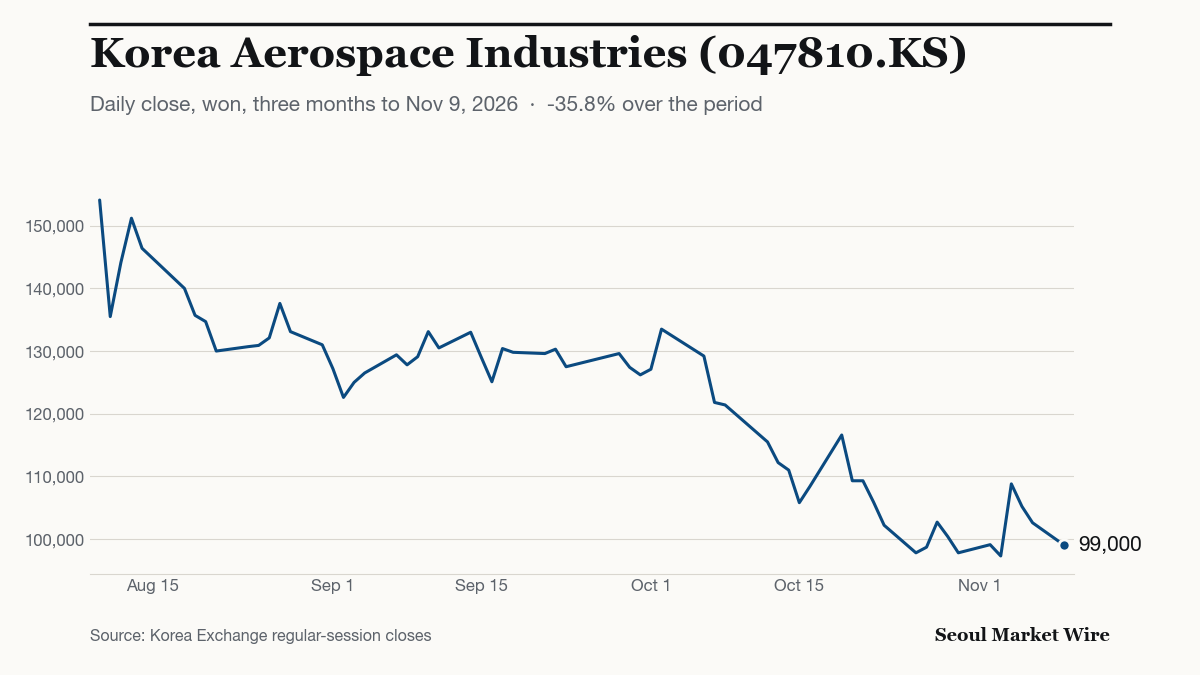
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-10 (KST)
Korea Aerospace Industries (KAI) reported third-quarter operating profit above consensus, but Shinhan Securities’ Nov. 4 adjustment turns the beat into a miss. The brokerage estimated operating profit at 69.4 billion won after subtracting a 40 billion won currency benefit and adding back 30 billion won in one-off costs. The adjusted figure was 8.7% below the 76 billion won consensus cited by Shinhan. It maintained Buy, citing expected fourth-quarter deliveries and new orders.
Reported operating profit rose 31.9% from a year earlier to 79.4 billion won, while revenue increased 51.6% to 1.0643 trillion won. This review covers ten brokerage reports published on Nov. 4, rather than all firms covering KAI.
How much of the beat came from currency adjustments?
The stronger won lowered estimated costs on aircraft export contracts, lifting operating profit. The benefit was about 40 billion won in the Nov. 4 estimates from Kiwoom Securities and SK Securities, compared with about 30 billion won in Yuanta Securities Korea’s report that day.
Several brokers identified about 30 billion won in one-off costs: 12 billion won in bad-debt provisions for Iraq receivables, 11 billion won in warranty provisions and 7 billion won in G280 loss provisions. A broader tally from Hanwha Investment & Securities on Nov. 4 included consolidation adjustments and reached about 37 billion won, nearly offsetting the 40 billion won currency benefit.
How do the targets and valuations compare?
All ten reviewed reports rate KAI Buy. Their targets range from 135,000 won to 186,000 won, with a median of 161,500 won and a mean of 162,000 won. The mean target was 60.1% above KAI’s Nov. 10 KRX close of 101,200 won, as recorded on the company’s IR price-history page.
| Brokerage | Date | Rating | Target Price |
|---|---|---|---|
| DS Investment & Securities | Nov. 4 | Buy | 186,000 won |
| Kiwoom Securities | Nov. 4 | Buy | 185,000 won |
| Yuanta Securities Korea | Nov. 4 | Buy | 182,000 won |
| Daishin Securities | Nov. 4 | Buy | 173,000 won |
| Mirae Asset Securities | Nov. 4 | Buy | 173,000 won |
| Hanwha Investment & Securities | Nov. 4 | Buy | 150,000 won |
| SK Securities | Nov. 4 | Buy | 150,000 won |
| Eugene Investment & Securities | Nov. 4 | Buy | 146,000 won |
| Shinhan Securities | Nov. 4 | Buy | 140,000 won |
| iM Securities | Nov. 4 | Buy | 135,000 won |
The valuation comparisons use different earnings horizons. In its Nov. 4 report, Daishin Securities valued KAI at 20.3 times 36-month forward earnings, against a global peer average of 18.0 times. For its target, the report’s narrative specifies a P/E multiple of 30.8 times estimated 2028 earnings attributable to controlling shareholders.
By contrast, Eugene Investment & Securities’ Nov. 4 report put KAI at 24.2 times 12-month forward earnings, below its historical average of 26.5 times. Those multiples are not directly comparable with Daishin’s longer-horizon figures.
What would support a fourth-quarter improvement?
Both Yuanta and Eugene expect fourth-quarter improvement. Yuanta forecasts record quarterly revenue, including at least six domestic KF-21 fighter deliveries and two or three Light Armed Helicopter (LAH) deliveries. Eugene estimates operating profit could exceed 100 billion won if no additional provisions arise.
How much new business is still needed?
To reach the 10.4 trillion won annual order target, Eugene estimates KAI needs about 8.2 trillion won in additional orders. That is a remaining requirement, not secured business.
What could hold back revenue and profit?
Delivery delays threaten revenue. In its Nov. 4 assessment, iM Securities described engine defects disrupting about 20 LAH deliveries planned for 2026 and a potential revenue shortfall of 400–500 billion won against KAI’s initial 5.7 trillion won guidance. Shinhan’s account of KAI’s earnings call also records company comments anticipating a shortfall of that size. These accounts do not establish that KAI issued a separate formal guidance-revision disclosure. SK forecast annual revenue of about 5.2 trillion won.
Further Iraq bad-debt provisions and in-house development spending could limit profit, Yuanta cautioned. It estimated fourth-quarter development spending of up to 100 billion won, compared with 60 billion won in the first three quarters combined.
Sources
- Shinhan Securities — KAI: Time to prove it with deliveries and orders (Nov. 4, 2026) stock.naver.com
- Yuanta Securities Korea — KAI 3Q26 review: a surprise on earnings and orders (Nov. 4, 2026) stock.naver.com
- Eugene Investment & Securities — KAI: Everything is bottoming out (Nov. 4, 2026) stock.naver.com
- iM Securities — KAI 3Q26: the start of a defence-order revival? (Nov. 4, 2026) stock.naver.com
- Daishin Securities — KAI 3Q26 review: mass-production revenue ramps up at home and abroad (Nov. 4, 2026) stock.naver.com
8 more sources
- Kiwoom Securities — KAI: Fourth-quarter orders are key (Nov. 4, 2026) stock.naver.com
- Hanwha Investment & Securities — KAI 3Q26 review (Nov. 4, 2026) stock.naver.com
- DS Investment & Securities — KAI: Confidence behind the annual order guidance (Nov. 4, 2026) stock.naver.com
- Mirae Asset Securities — KAI: Potential in earnings and orders (Nov. 4, 2026) stock.naver.com
- SK Securities — KAI: Growth in 2027–28 and year-end orders (Nov. 4, 2026) stock.naver.com
- iM Securities — Official KAI research publication (Nov. 4, 2026) imfnsec.tistory.com
- Shinhan Securities — KAI report and earnings-call Q&A (Nov. 4, 2026) bbs2.shinhansec.com
- Korea Aerospace Industries IR — Daily share-price history ir.gsifn.io