Brokerages see a valuation trough for K-pop agencies, but earnings outlooks differ
Brokerages see scope for K-pop shares to recover, but their profit forecasts use different company coverage and treatment of a HYBE charge. Newer acts' profitability remains central.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-13 (KST)
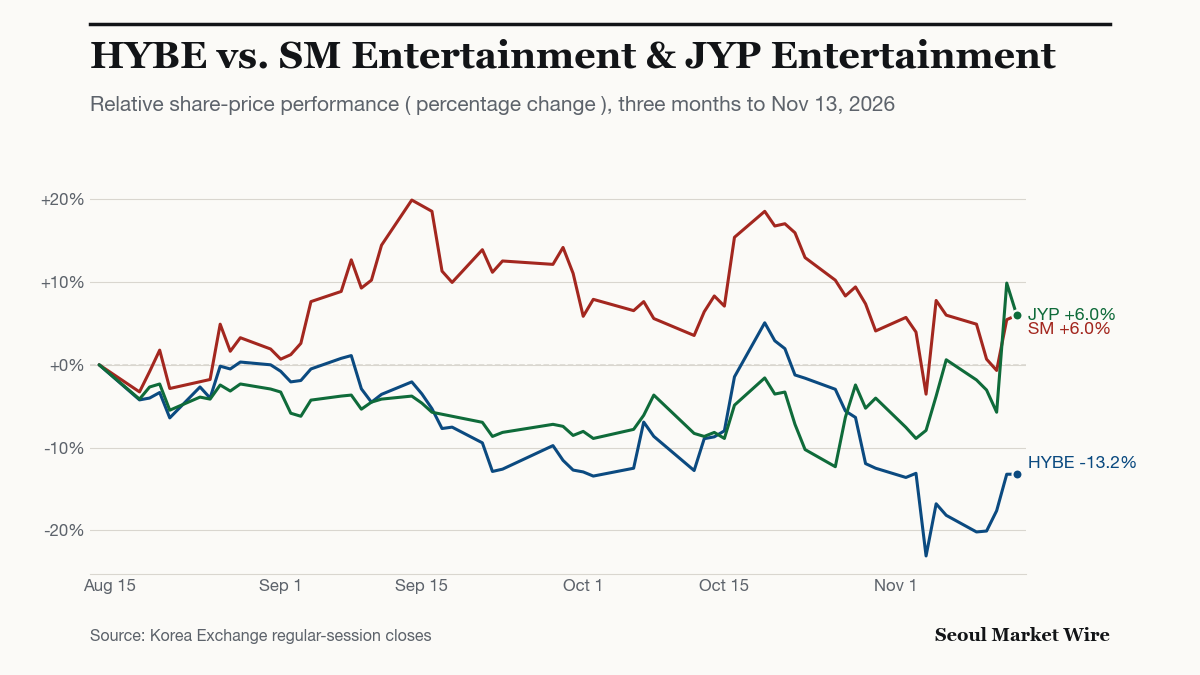
Brokerages see room for K-pop shares to recover, but their 2027 profit forecasts point in opposite directions. Reports published Nov. 9–12, 2026, pair a valuation-trough argument with different company coverage and treatment of a HYBE one-off charge, making the growth rates unsuitable for a direct comparison.
What supports the valuation case?
Lower expectations underpin Yuanta Securities’ Nov. 12 assessment. After cutting its valuation bands twice in 2026, the brokerage places SM Entertainment, JYP Entertainment and YG Entertainment near the lower end of those bands, with HYBE below its band. Its argument rests on earnings recovery within reduced valuation ranges.
Historical market capitalisation informs Shinhan Investment Corp.’s Nov. 11 case. Using Nov. 10 closes, it places the combined value of HYBE, SM, JYP, YG and DearU near 11 trillion won, comparable with lows in October 2022 and September 2024. That comparison concerns aggregate equity value, rather than an earnings multiple or proof of a lasting bottom.
When could earnings recover?
Both forecasts measure operating profit, but the company lists and 2026 comparison bases differ:
| Forecast | Companies | Treatment of the 2026 HYBE charge |
|---|---|---|
| Yuanta | HYBE, SM, JYP, YG | Included in its 2026 profit estimate; its 2027 recovery assumes the charge does not recur. |
| Shinhan | The same four plus DearU | A 255 billion won first-quarter share-gift charge is excluded from the 2026 comparison base. |
For the four agencies, Yuanta projects 2027 operating profit of 916.2 billion won, up 32.6% from 691.2 billion won in 2026. Excluding HYBE, it forecasts a 9.1% decline in 2026 followed by a 9.8% increase in 2027. Its HYBE analysis explicitly identifies the absence of the first-quarter 2026 charge as one contributor to recovery.
By contrast, Shinhan forecasts five-company operating profit of 994.6 billion won in 2027, down 4% against its adjusted 2026 base. The adjustment removes the charge from the earlier year; it is not a deduction from the 2027 forecast. Coverage and accounting treatment therefore need to be aligned before comparing the growth rates.
Newer acts also contribute to Yuanta’s earnings case. The brokerage expects groups launched in 2022–23 to generate stronger agency profits before renewals, while those launched in 2024–25 begin recouping investment. These are its profitability assumptions, not universal contract rules.
For 2028, Shinhan anticipates a profit cycle larger than 2026’s, assuming a BTS comeback, a full SEVENTEEN lineup, growth from newer acts and recurring activity by established groups. Those are brokerage assumptions, rather than confirmed company schedules.
Which stocks do the brokers prefer?
Short-term preference at Yuanta goes to SM, reflecting valuation and expected greater activity by NCT WISH and Hearts2Hearts. HYBE is its medium-term preference.
The Nov. 11 outlook from Hana Securities selects HYBE as its top entertainment pick, citing expected further BTS activity and a new US boy-group debut. YG is on its watch list, with new boy and girl groups expected to debut sequentially, potentially as early as the first half of 2027. These debut timings are the brokerage’s expectations.
What does the media evidence show?
A redistribution of TV advertising supports Shinhan’s 2027 media case. Its analysts expect CJ ENM and SBS to attract some advertising from financially strained competing channels. This is a market-share forecast, separate from quarterly results.
The brokerage’s Nov. 9 weekly reported third-quarter operating profit of 22.1 billion won at CJ ENM, 15.1 billion won at Studio Dragon, up 44% year on year, and 73.6 billion won at CJ CGV.
The but
Profitable newer acts matter more than debut announcements alone, argues Eugene Investment & Securities in its Nov. 12 outlook. Its analysts describe weaker links between album sales, concert expansion and rising share prices. Recovering past valuation levels requires newer artists to sustain earnings when major acts are inactive.
Currency effects pose a separate issue. Shinhan’s weekly attributes a reduction in HYBE’s third-quarter net profit to foreign-currency valuation and exchange losses as the won strengthened. It links agencies’ foreign-currency holdings to overseas receipts and fee and royalty settlements.
Streaming results also remained uneven: the same weekly reported TVING’s third-quarter 2026 operating loss at 7.2 billion won.
Sources
- Yuanta Securities — Entertainment 2027 outlook: a year of bottoming and rebound (이환욱; Nov. 12, 2026; pp. 1–5, 10) stock.naver.com
- Eugene Investment & Securities — 2027 outlook: a rebound is possible (이현지; Nov. 12, 2026; pp. 1, 6) stock.naver.com
- Hana Securities — The promised odd year is coming (이기훈; Nov. 11, 2026; p. 1) stock.naver.com
- Shinhan Investment Corp. — Why the odd year of 2027 is special (지인해; Nov. 11, 2026; pp. 1, 3, 9–10, 20) stock.naver.com
- Shinhan Investment Corp. — Platform team weekly: profitable curiosity, second week of November (entertainment/media/leisure: 지인해; Nov. 9, 2026; p. 1) stock.naver.com