Six of eight brokers reviewed cut PharmaResearch targets
Targets in the eight-report comparison range from 324,000 to 530,000 won. Export growth supported revenue, but a larger cosmetics contribution and CG USA expenses constrained profit.
Market data: Korea Exchange regular-session close & Hana Bank USD/KRW reference rate, 2026-11-16 (KST)
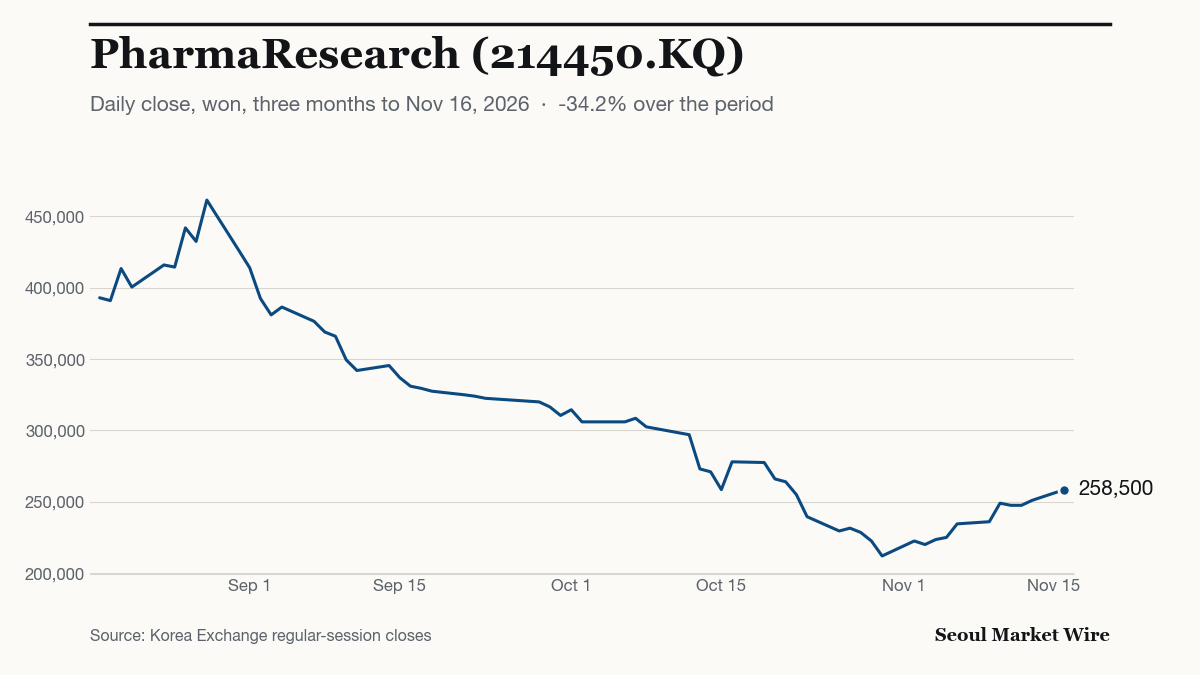
Among the eight Nov. 9 brokerage reports reviewed for this article, six lowered their price targets for PharmaResearch. Domestic medical-device sales stagnated and a larger cosmetics contribution weighed on margins, despite continued export growth.
Preliminary company results showed third-quarter revenue of 171.5 billion won, up about 27% from a year earlier, while operating profit rose just 1.2% to 62.6 billion won. The operating margin was 36.5%, down about 9 percentage points. CG USA acquisition costs and operating losses added to the pressure from the changing sales mix.
The disagreement concerns how much value to assign to that changing business. Exports are expanding, but the domestic device business that previously supported a valuation premium has slowed. The reports differ over the cause of that slowdown and how to assess the earnings result.
How far did targets move?
The largest reduction in this comparison came from IBK Securities, whose Nov. 9 report lowered its target 35.8% to 340,000 won from 530,000 won. The lowest target was Yuanta Securities Korea’s 324,000 won, a reduction of 28%.
The sole increase came from Kiwoom Securities, which raised its target 11.6% to 480,000 won from 430,000 won. At the top of the range, Kyobo Securities maintained 530,000 won.
The eight targets average 415,500 won, with a median of 415,000 won. Those figures describe this selection of Nov. 9 reports, rather than a complete market-wide consensus.
All prices below are in won per share; changes compare each firm’s Nov. 9 target with its previous target.
| Brokerage | Previous target | Nov. 9 target | Change |
|---|---|---|---|
| Kyobo Securities | 530,000 | 530,000 | Unchanged |
| Kiwoom Securities | 430,000 | 480,000 | +11.6% |
| Mirae Asset Securities | 600,000 | 450,000 | -25.0% |
| Daishin Securities | 460,000 | 420,000 | -8.7% |
| Shinhan Securities | 510,000 | 410,000 | -19.6% |
| Eugene Investment & Securities | 420,000 | 370,000 | -11.9% |
| IBK Securities | 530,000 | 340,000 | -35.8% |
| Yuanta Securities Korea | 450,000 | 324,000 | -28.0% |
Where did revenue growth come from?
Company data show flat domestic medical-device sales and strong export growth. Domestic device revenue was 57.1 billion won, little changed from a year earlier, while device exports increased about 53% to 30.0 billion won.
Cosmetics revenue rose about 76% to 62.0 billion won. Within that business, exports increased 92% to 42.1 billion won and domestic sales rose 50% to 19.9 billion won. Pharmaceutical sales fell 12% to 19.4 billion won.
Total exports reached 81.6 billion won, up 62%, compared with domestic revenue of 89.9 billion won, up 6%. Exports thus accounted for nearly half of quarterly revenue, while cosmetics contributed more than a third. Both proportions are calculated from the company’s reported sales.
That distribution matters for the earnings comparison: growth in the company’s total revenue does not imply a recovery in domestic devices. Cosmetics and device exports supplied growth while domestic device sales remained flat.
Did earnings miss expectations?
The reports differed in their assessment of the shortfall. Eugene Investment & Securities described earnings as broadly in line with lowered expectations in its Nov. 9 review. Its comparison table nevertheless showed operating profit below a consensus estimate of 66.4 billion won.
Against that benchmark, reported operating profit of 62.6 billion won was approximately 3.8 billion won, or 6%, lower. Yuanta used the same 66.4 billion won benchmark and called the result a miss.
Other assessments also varied. In its Nov. 9 review, Mirae Asset Securities described both revenue and operating profit as meeting market expectations. Kiwoom characterised the quarter as slightly below expectations that had already been reduced.
The distinction is in the analysts’ descriptions, not an established difference between the benchmarks. Eugene’s broadly-in-line assessment coexists with a shortfall in its own table; Yuanta described a shortfall against the same operating-profit estimate as a miss.
Why did domestic device sales stall?
Lower spending by foreign visitors at Korean dermatology clinics explained the domestic device weakness in Eugene’s analysis.
The opposite interpretation appeared in IBK’s review: foreign medical-tourism demand remained firm, while weaker spending by Korean patients restrained domestic device revenue. These are competing brokerage explanations. The segment’s flat sales alone cannot establish which customer group contributed most to the slowdown.
A sequential recovery would not necessarily mean a return to earlier growth rates. Eugene projected fourth-quarter domestic device sales growth of 8% from the third quarter but only 3% from a year earlier. Its analysts cautioned that the business was unlikely to regain its previous pace of expansion.
What valuation can the new sales mix support?
The speed of domestic recovery and repeat orders from new overseas cosmetics channels were questions raised by Daishin Securities in its Nov. 9 assessment. The brokerage lowered its target to 420,000 won from 460,000 won.
For Eugene, slower domestic device growth and a larger cosmetics contribution justified a reduction in the premium previously attached to fast-growing, high-margin domestic Rejuran sales. Its growth case rests increasingly on overseas expansion.
The brokerage forecasts 2027 revenue of 828.0 billion won, up 23%, and operating profit of 297.2 billion won, up 21%. It expects exports to account for 52% of sales, an increase of 6 percentage points.
Those estimates illustrate the distinction between profit growth and margin recovery. Operating profit can rise as sales expand even when profit grows more slowly than revenue. Eugene’s 2027 estimates imply an operating margin of about 36%, close to the third quarter’s 36.5%.
Which margin pressures could persist?
CG USA acquisition costs and consolidated operating losses totalled about 3.5 billion won in the third quarter, according to Eugene. That combined amount includes losses from the acquired business and cannot be treated entirely as a one-off acquisition expense.
The sales mix presents a separate source of pressure. Faster cosmetics growth can increase total profit while reducing the percentage of revenue retained as operating profit. A recovery in domestic device sales therefore need not restore the company’s previous margin if cosmetics continue to gain sales share.
For the fourth quarter, Eugene expects operating profit to decline sequentially despite revenue growth. Its forecasts are 178.2 billion won in revenue and 59.6 billion won in operating profit, implying an operating margin of about 33%, below the third quarter’s 36.5%.
The forecast includes higher advertising spending, including an estimated 3.0 billion won in costs for the PharmaResearch Global Symposium (PGS).
Sources
- PharmaResearch — Preliminary third-quarter 2026 results pharmaresearch.com
- Yuanta Securities Korea — PharmaResearch: Exports lead growth as margins take a breather (2026-11-09) stock.naver.com
- IBK Securities — PharmaResearch: Time to focus on export-led growth (2026-11-09) stock.naver.com
- Eugene Investment & Securities — PharmaResearch 3Q26 review: Focus on profit growth over margins (2026-11-09) stock.naver.com
- Eugene Investment & Securities — Full PharmaResearch report (2026-11-09) consensus.hankyung.com
8 more sources
- Daishin Securities — PharmaResearch: The share-price bottom has passed (2026-11-09) stock.naver.com
- Kiwoom Securities — PharmaResearch: The CEO's philosophy comes into view (2026-11-09) stock.naver.com
- Kyobo Securities — PharmaResearch 3Q26 review (2026-11-09) stock.naver.com
- Mirae Asset Securities — PharmaResearch 3Q26 review (2026-11-09) stock.naver.com
- Shinhan Securities — PharmaResearch: Growth evident despite concerns (2026-11-09) stock.naver.com
- IBK Securities — PharmaResearch previous target (2026-08-10) stock.naver.com
- Yuanta Securities Korea — PharmaResearch previous target (2026-08-10) stock.naver.com
- Kiwoom Securities — PharmaResearch previous target (2026-10-28) stock.naver.com